←Home/Templates/Finance/Lending/Portfolio Loan Checklist: Non-Conforming Mortgage

Portfolio Loan Checklist: Non-Conforming Mortgage

Portfolio and Relationship Lending Resource

Streamline your portfolio loan application with our comprehensive document checklist. For borrowers and community banks or credit unions that keep the loan on their balance sheet. Portfolio lending can stretch on unique properties, entity vesting, residual income, or relationship deposits. Gather a complete credit file plus the exception story, property uniqueness docs, and reserve support the credit committee will want.
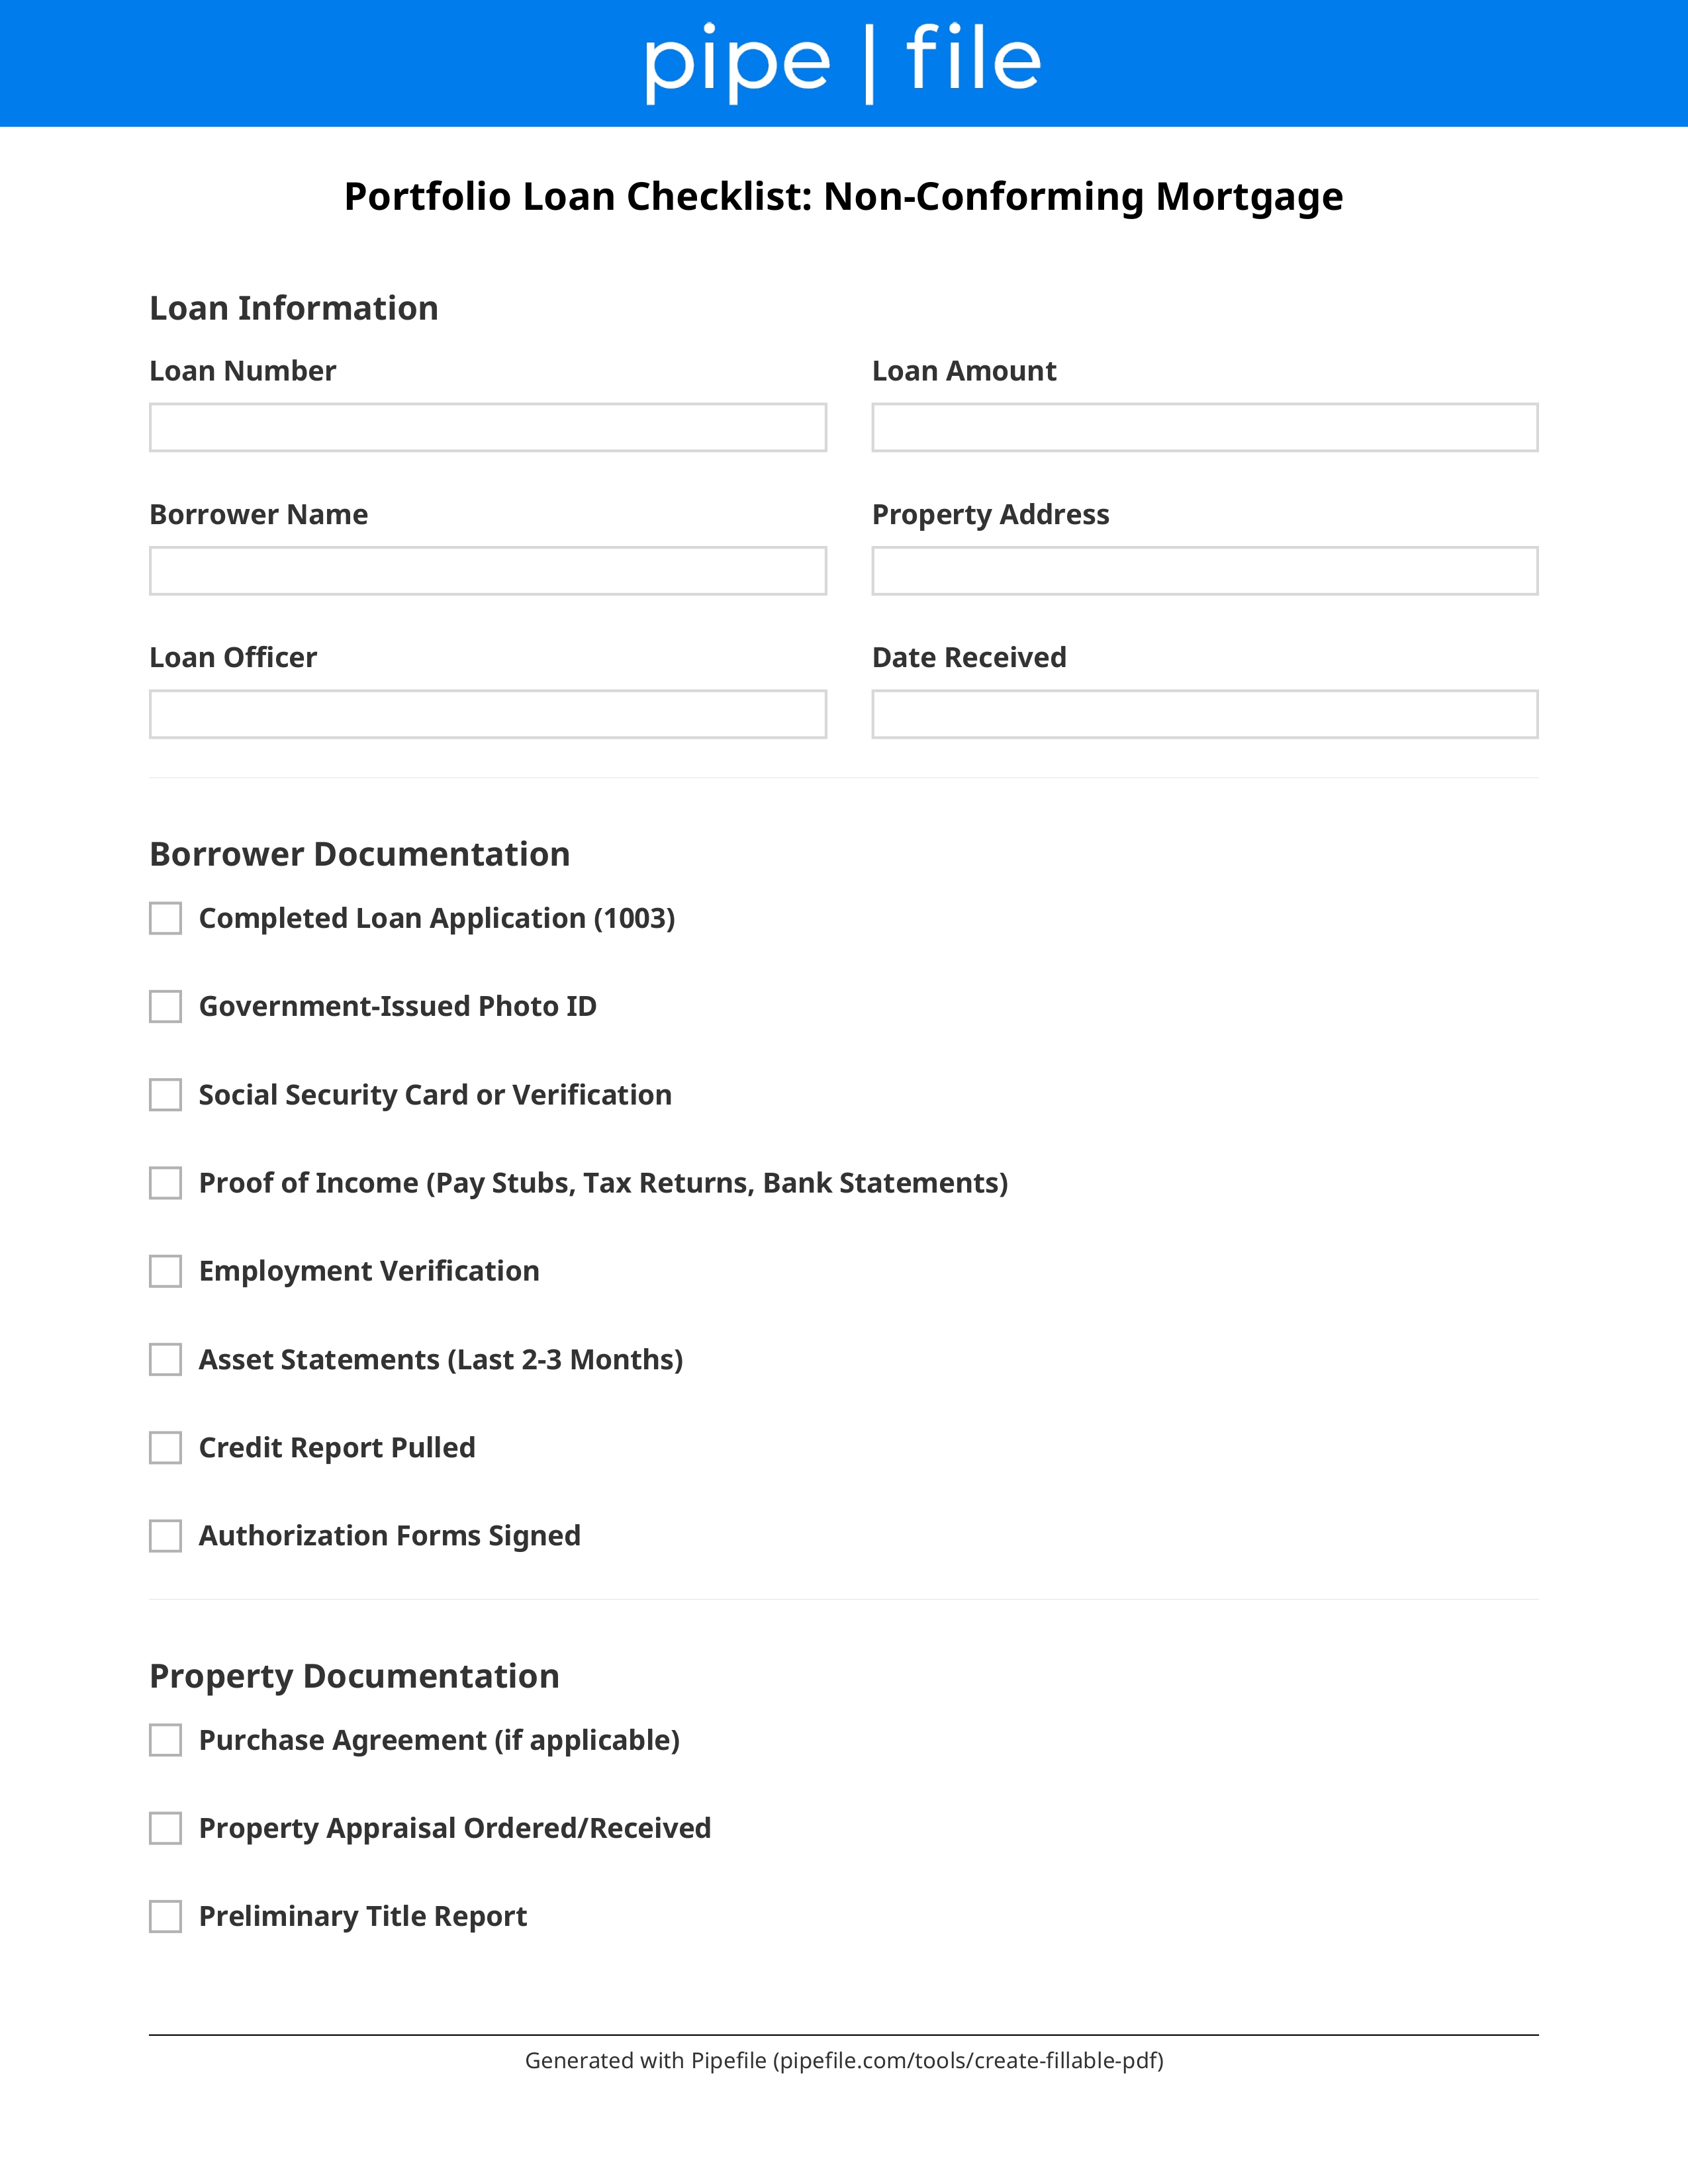
Portfolio Loan Checklist: Non-Conforming Mortgage form template preview

Key Benefits

Present a complete file plus a clear exception narrative
Document unique property, acreage, or mixed-use features
Support residual income, deposits, or relationship strength
Prepare entity vesting and guarantee documents
Reduce credit-committee conditions
Professional portfolio-lending workflow

Common Use Cases

Borrowers with unique properties that agency guidelines rejectCommunity banks underwriting relationship mortgagesMixed-use, acreage, or condotel propertiesEntity-vested second homes or rentalsBorrowers needing a manual exception on DTI or reservesCredit unions holding loans in portfolio

Frequently Asked Questions

What is a portfolio loan?
A portfolio loan is held on the lender's balance sheet instead of being sold to Fannie Mae, Freddie Mac, or a jumbo investor with rigid overlays. The bank can make exceptions for unique property, income, or relationship. Pricing and prepayment terms are set by that institution.
When should I seek a portfolio loan?
Use portfolio when the property or borrower falls outside agency or Non-QM boxes: acreage, mixed-use, condotels, unusual vesting, residual-income stories, or a deep deposit relationship. Expect a credit-committee narrative, not just a DU findings printout.
What extra documents do portfolio lenders want?
A full mortgage file plus an exception memo, unique-property exhibits (survey, zoning, photos, business-use notes), relationship or deposit history, and sometimes a personal financial statement. Terms, prepay, and recourse are negotiated in the commitment.
Are portfolio rates higher than conforming?
Often yes, because the bank keeps the credit risk. Relationship pricing, compensating deposits, or a shorter term can offset. Compare the all-in cost and prepayment language against jumbo and Non-QM investor products.

Checklist

Application

Complete loan application and exception request
Required

State why agency or investor guidelines do not fit and what exception you need.

Borrower Documentation

Income, asset, and reserve documentation
Required

Full file even if the exception is property-related. Residual income if used.

Property Documentation

Unique property exhibits (survey, zoning, photos, business use)
Required

Acreage, mixed-use, accessory units, or condotel docs the committee will ask for.

Underwriting

Written exception or relationship narrative
Required

Compensating factors: reserves, LTV, deposits, payment history, residual income.

Business Documentation

Entity documents and guarantees if vesting is not individual

Articles, operating agreement, borrowing resolution, and personal guarantees.

Credit

Credit authorization and housing-history explanations
Required

Manual underwriting still needs a clean story on lates or thin credit.

Valuation

Appraisal that addresses the unique features
Required

Lender-ordered. Comparable selection must support the exception property.

Identity

Government-issued photo ID for all borrowers and guarantors
Required

Driver's license or passport.