←Home/Templates/Finance/Lending/Investment Property Loan Checklist: Document Requirements

Investment Property Loan Checklist: Document Requirements

Rental Property and Investor Mortgage Resource

Streamline your investment property loan application with our comprehensive document checklist. For real estate investors, brokers, and lenders financing 1-4 unit or small-balance rental properties. Gather purchase or refinance docs, leases and rent rolls, borrower income or DSCR support, reserves, entity documents, and insurance so the file meets investor-program overlays.
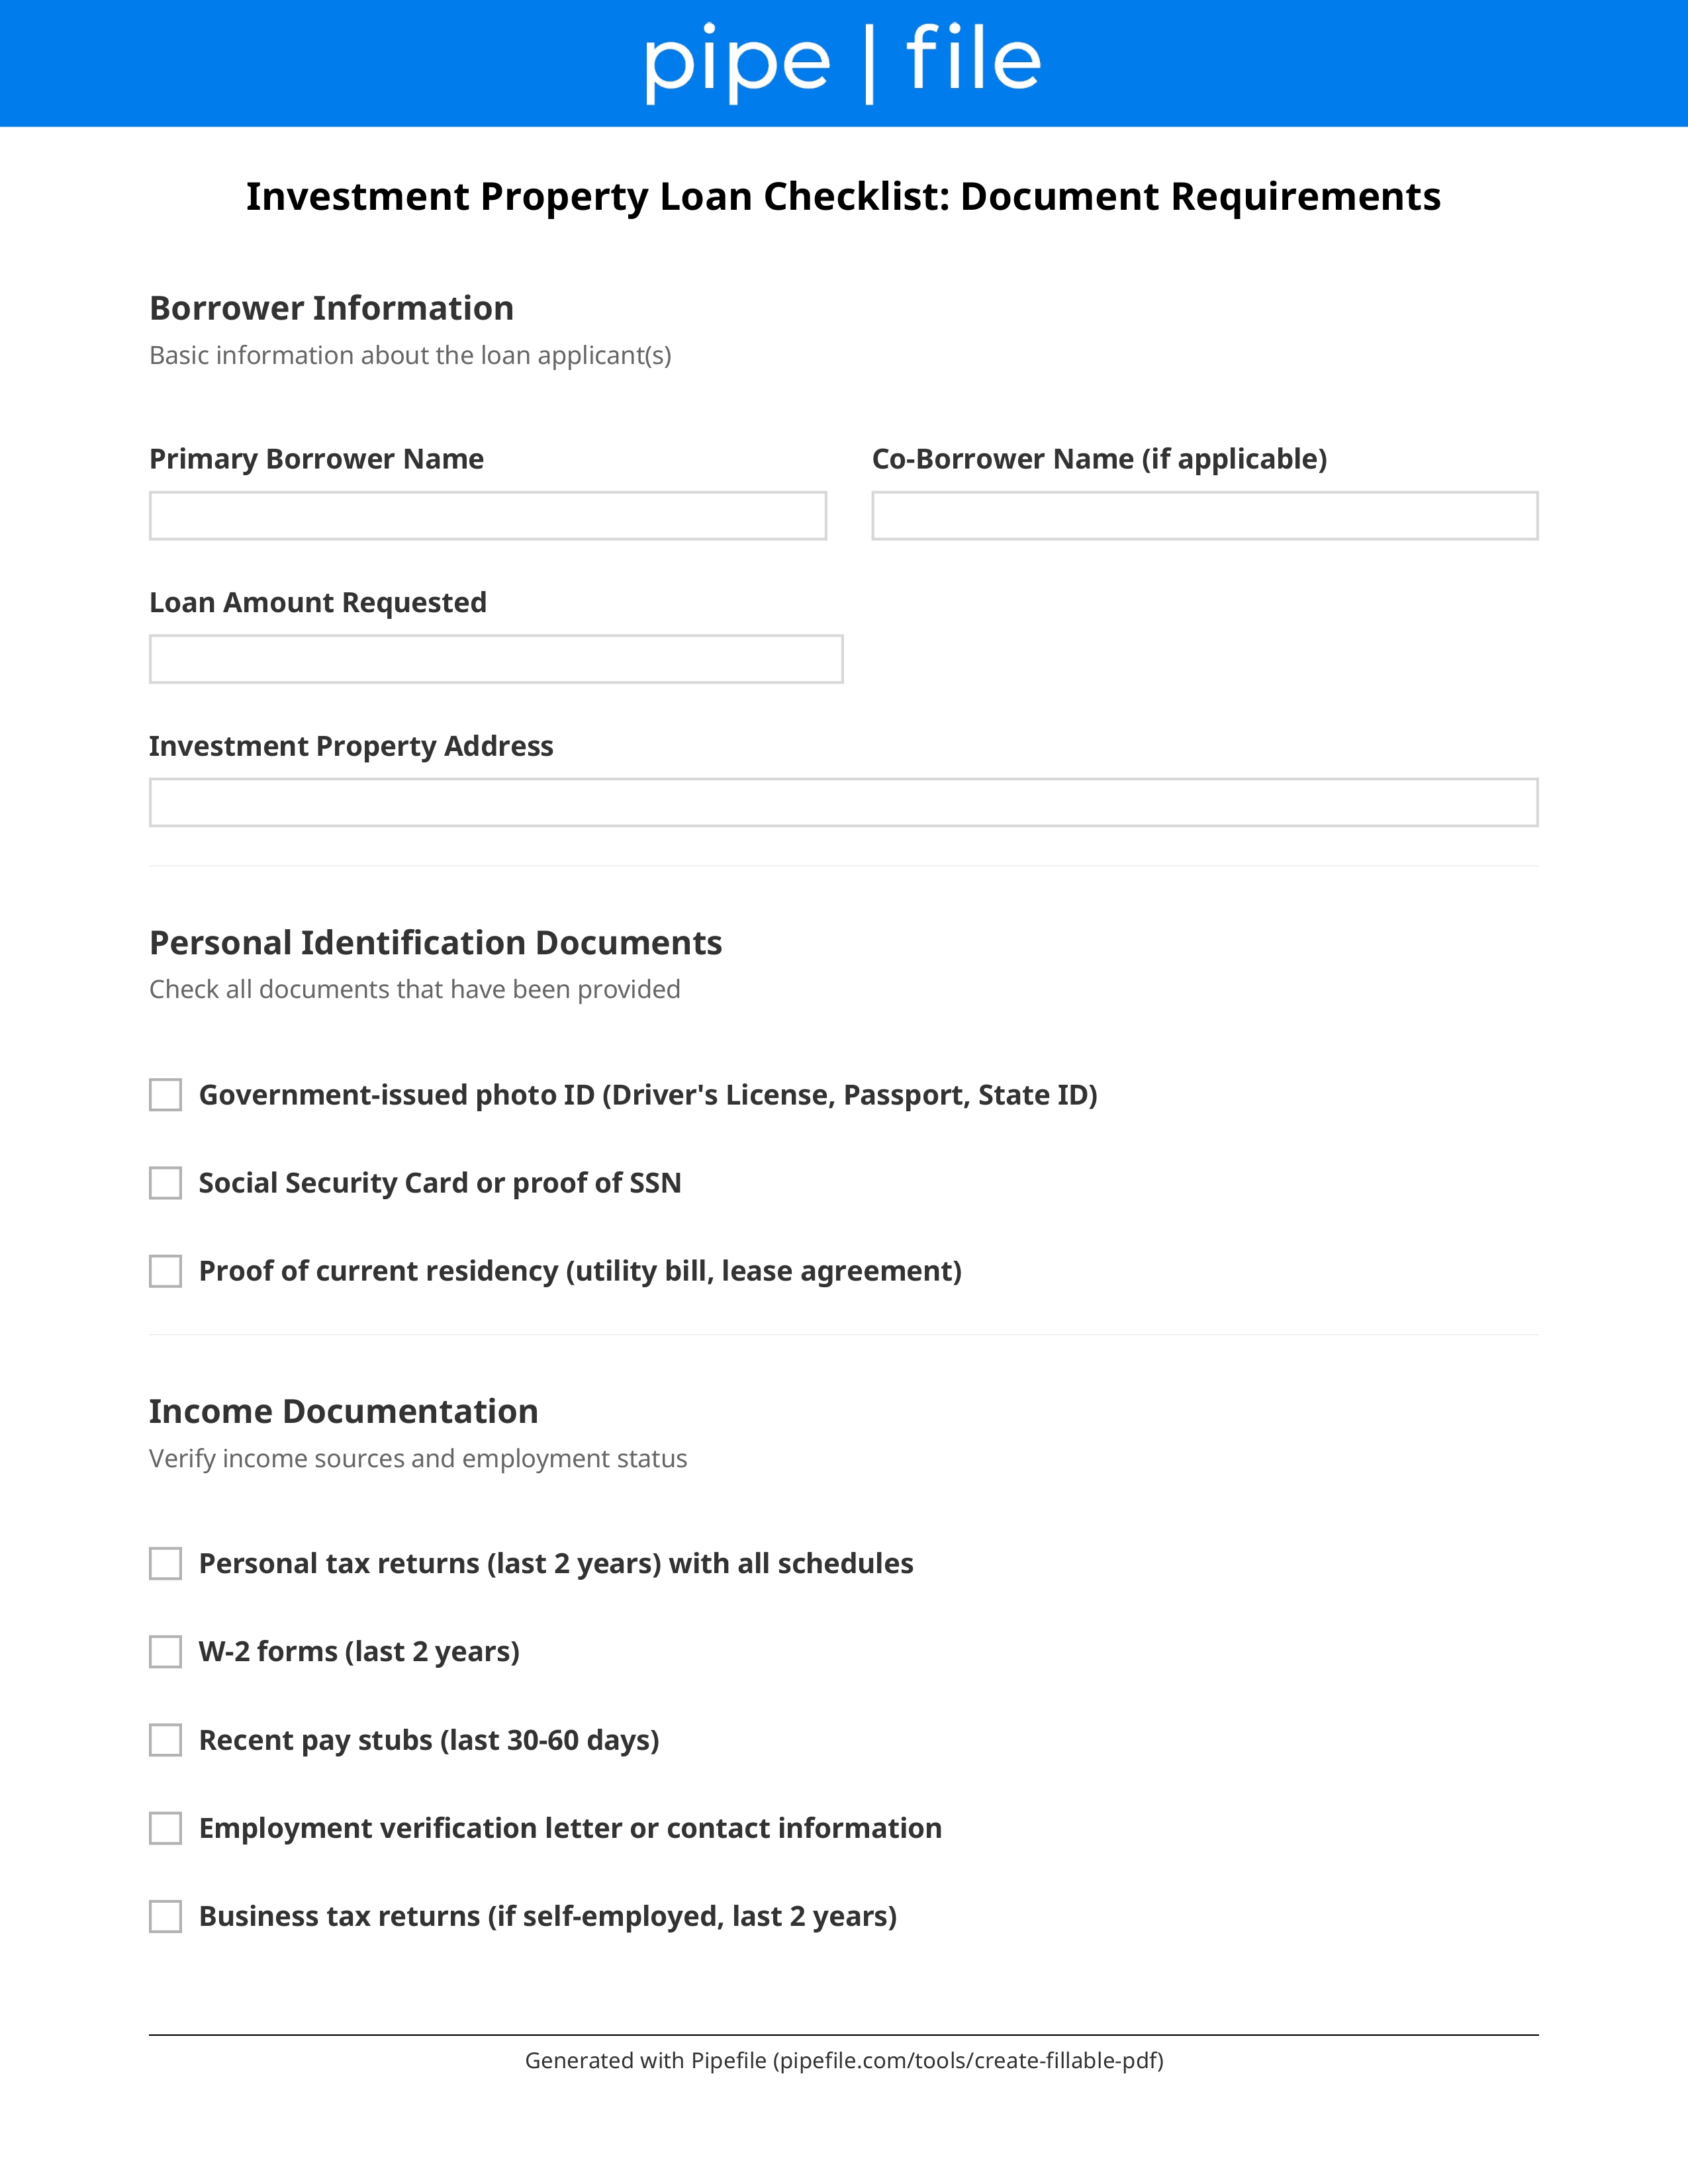
Investment Property Loan Checklist: Document Requirements form template preview

Key Benefits

Collect leases, rent rolls, and property financials
Document borrower income or DSCR qualification
Meet higher reserve requirements on rentals
Prepare LLC or entity borrowing documents
Reduce conditions on investor mortgage programs
Professional rental-property lending workflow

Common Use Cases

Investors purchasing a 1-4 unit rentalCash-out or rate-and-term refinance on a rentalLoan officers originating investor or DSCR loansBorrowers moving a property from flip to holdLLCs financing rentals in an entity nameUnderwriters verifying rents and reserves

Frequently Asked Questions

How do investment property loans differ from primary mortgages?
Investor loans usually need larger down payments, higher rates, and more reserves. Lenders may qualify on borrower income (conventional/non-QM) or on the property's DSCR. Leases, rent rolls, and landlord insurance replace occupancy affidavits used on a primary residence.
What documents prove rental income?
In-place leases, a rent roll, and sometimes deposit history or tax Schedule E. Vacant units may use market rents from an appraisal or 1007. DSCR programs focus on leases and PITIA rather than personal tax returns.
Can I close in an LLC?
Many investor and DSCR programs allow entity vesting. You will need articles, operating agreement, EIN, and authorization to borrow, plus personal guarantees from the members. Conventional agency loans are more restrictive on entity vesting.
How many months of reserves are required?
Investor programs often want 6-12 months of PITIA (sometimes more for multiple financed properties). Reserves must be documented with statements. Gift funds usually cannot satisfy reserve requirements.

Checklist

Application

Loan application for the investment property
Required

Occupancy as investment. Entity vs. individual vesting. All members if required.

Transaction

Purchase contract or current mortgage statement and payoff
Required

Refinances need existing loan details and purpose (rate-term or cash-out).

Property Income

Current leases and rent roll (or market-rent support if vacant)
Required

In-place rents, terms, and deposits. Vacant units need appraisal 1007 or comps.

Income Documentation

Borrower income docs or DSCR package per program
Required

W-2/returns for conventional; leases and PITIA for DSCR; bank statements for some Non-QM.

Asset Documentation

Asset statements documenting required PITIA reserves
Required

All pages. Typically 6-12 months. Gift funds usually do not count.

Property Documentation

Landlord or dwelling insurance quote and any HOA docs
Required

Investment coverage, not a primary HO-3 if the lender requires landlord form.

Business Documentation

LLC or entity documents if title will vest in an entity

Articles, operating agreement, EIN, and borrowing resolution.

Identity

Government-issued photo ID for all borrowers and guarantors
Required

Driver's license or passport. Credit authorization for each.