←Home/Templates/Finance/Lending/Jumbo Loan Checklist: Document Requirements

Jumbo Loan Checklist: Document Requirements

Jumbo Mortgage and High-Balance Lending Resource

Streamline your jumbo loan application with our comprehensive document checklist. For homebuyers, refinancers, and loan officers originating mortgages above the conforming limit. Jumbo underwriting is stricter on income, assets, reserves, and credit. Gather a complete 1003 file plus extra statements, large-deposit explanations, and reserve documentation so conditions stay short.
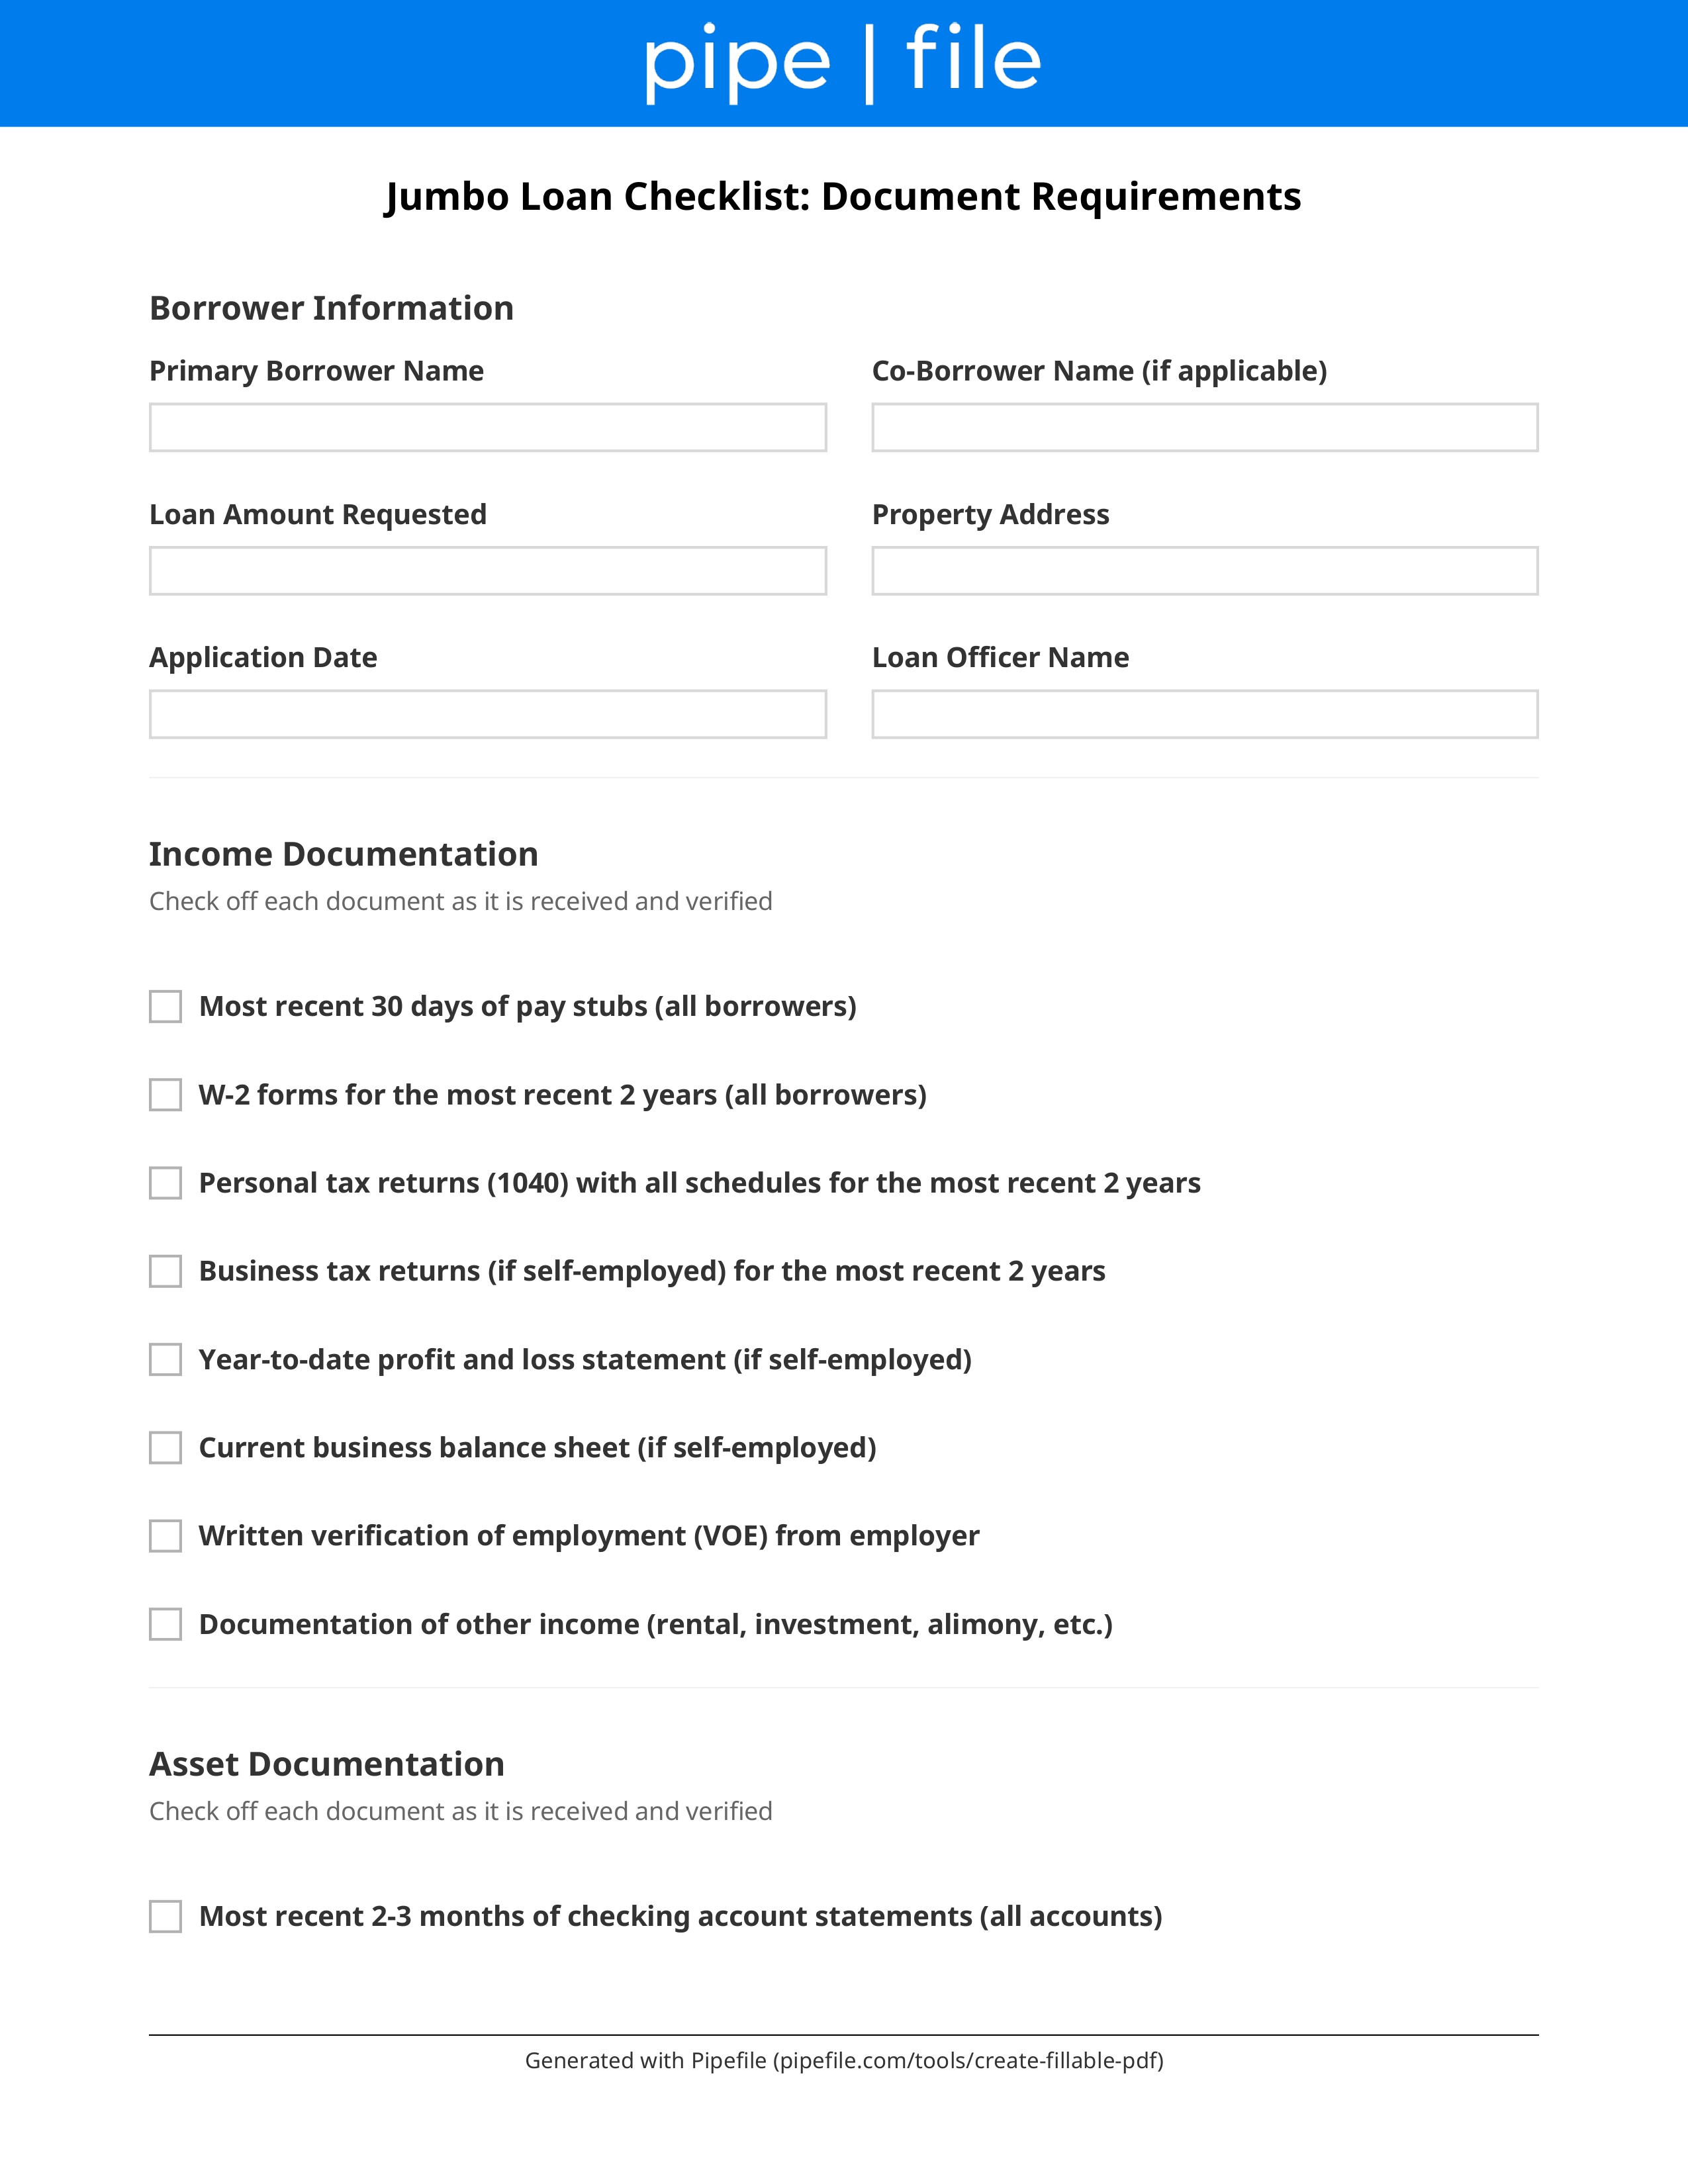
Jumbo Loan Checklist: Document Requirements form template preview

Key Benefits

Meet jumbo overlays on income and asset documentation
Document larger reserve requirements after closing
Explain large deposits and gift funds correctly
Prepare appraisal and property items for high-value homes
Reduce conditions on non-conforming purchase or refinance
Professional jumbo origination workflow

Common Use Cases

Buyers purchasing above the conforming loan limitHomeowners refinancing a jumbo balanceLoan officers originating jumbo or super-jumbo filesSelf-employed borrowers pairing jumbo with alt-doc incomeHigh-net-worth clients using asset depletion plus jumboUnderwriters clearing jumbo conditions before lock expiration

Frequently Asked Questions

What is a jumbo loan?
A jumbo loan exceeds the FHFA conforming limit for the county (and any high-balance conforming cap). It cannot be sold to Fannie Mae or Freddie Mac as a standard conforming loan. Lenders keep it in portfolio or sell it to jumbo investors, so overlays on credit, reserves, and documentation are typically tighter.
What extra documents do jumbo lenders want?
Beyond a conventional file, expect more months of asset statements, larger reserve requirements (often 6-24 months of PITIA), letters for large deposits, sometimes two appraisals on very high-value properties, and fuller tax-return packages for self-employed borrowers.
Are credit score and DTI overlays higher?
Often yes. Many jumbo programs want higher scores, lower DTI, and more down payment than conforming. Compensating factors (reserves, residual income, strong assets) can offset. Your loan officer should price overlays before you write the offer.
Can I use gift funds on a jumbo?
Some jumbo programs allow gifts for part of the down payment; many still require the borrower to contribute a minimum from their own seasoned funds, and gifts rarely count toward reserves. Get the gift letter and donor paper trail in the file early.

Checklist

Application

Uniform Residential Loan Application (1003)
Required

Complete income, assets, housing history, and declarations. All borrowers.

Credit authorization and explanations for derogatory items
Required

Jumbo overlays on score and housing history are typically stricter.

Income Documentation

Pay stubs, W-2s, and federal tax returns (typically 2 years)
Required

Self-employed: all schedules, K-1s, and YTD P&L. 4506-C as required.

Asset Documentation

Asset statements (typically 2 months, all pages) for down payment and reserves
Required

Jumbo reserves are often 6-24 months of PITIA. Include all pages.

Letters of explanation and paper trail for large deposits

Source any deposit that is not regular payroll. Gifts need a gift letter.

Property Documentation

Purchase contract or refinance payoff and title info
Required

Amendments included. Refinance: current statement and purpose.

Appraisal (and second appraisal if the program requires it)
Required

Lender-ordered. Very high-value or unique homes may need two reports.

Identity

Government-issued photo ID for all borrowers
Required

Driver's license or passport. Plus residency documents if applicable.