←Home/Templates/Finance/Lending/Non-QM Loan Checklist: Non-Qualified Mortgage Requirements

Non-QM Loan Checklist: Non-Qualified Mortgage Requirements

Non-Qualified Mortgage and Alternative Documentation Resource

Streamline your Non-QM loan application with our comprehensive document checklist. For borrowers who do not fit Qualified Mortgage rules (self-employed, investor, foreign national, or unique credit) and for Non-QM lenders. Cover the chosen income method (bank statements, P&L, asset depletion, DSCR), reserves, credit explanations, and property documents so the file matches the program overlays.
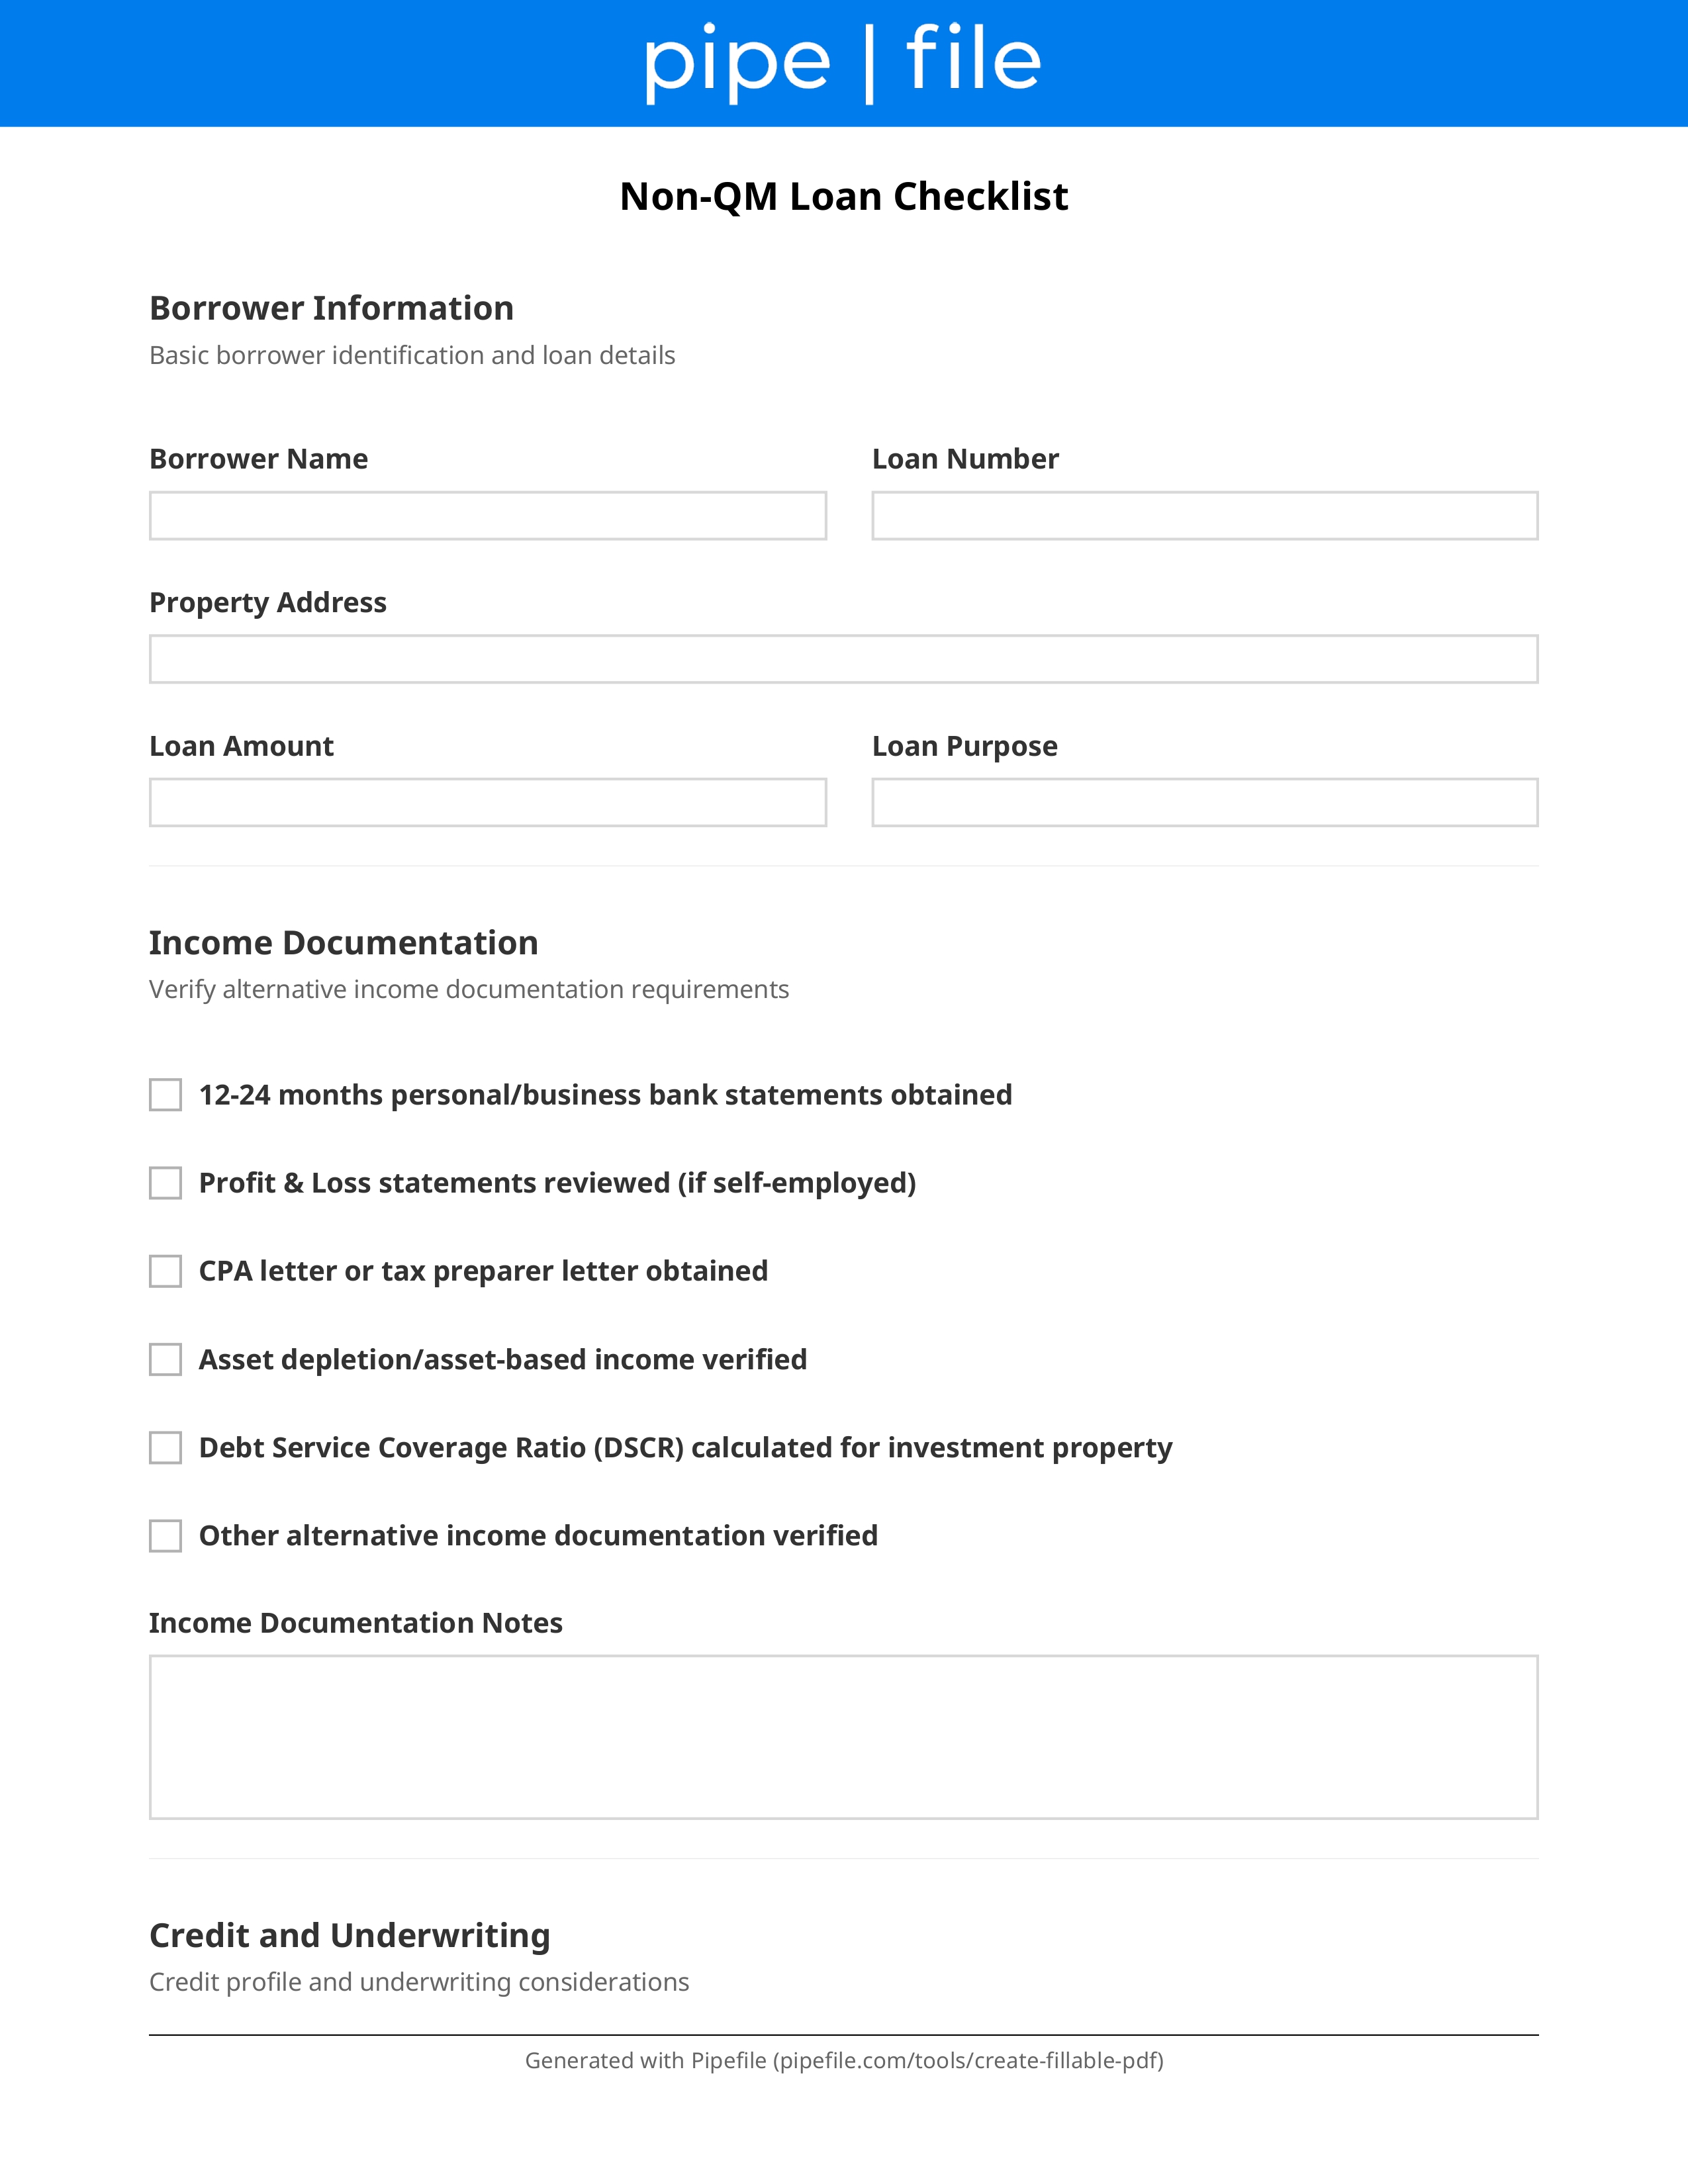
Non-QM Loan Checklist: Non-Qualified Mortgage Requirements form template preview

Key Benefits

Match documents to the Non-QM income method you are using
Gather bank statements, P&L, assets, or DSCR support
Document reserves and compensating factors
Explain credit events that QM programs will not accept
Reduce conditions on alternative-documentation files
Professional Non-QM origination workflow

Common Use Cases

Self-employed borrowers using bank-statement or P&L programsInvestors using DSCR instead of personal incomeBorrowers with recent credit events seeking Non-QMForeign nationals with alternative income documentationLoan officers choosing among Non-QM overlaysUnderwriters reviewing alt-doc income calculations

Frequently Asked Questions

What is a Non-QM loan?
A Non-Qualified Mortgage does not meet CFPB Qualified Mortgage criteria (for example DTI, documentation, or product features). Non-QM is legal and common for self-employed, investor, and unique-credit borrowers. Pricing is typically higher than conforming QM, and each investor has its own overlays.
What income methods do Non-QM programs use?
Common methods include 12- or 24-month bank statements, CPA-prepared P&L, asset depletion, DSCR on rentals, and sometimes 1099-only. You still need a full application, credit, assets, and property docs. Pick one method and gather that package completely.
Do Non-QM loans require more reserves?
Usually yes. Many programs want 6-12+ months of PITIA, and more on investment properties or lower credit scores. Reserves must be seasoned and documented. Gift funds rarely count toward the reserve requirement.
Can I get Non-QM after a foreclosure or bankruptcy?
Some Non-QM investors allow shorter seasoning than agency QM (for example 12-36 months). You will need explanations, a clean recent housing history, and stronger reserves. Exact wait periods are overlay-driven, not one national rule.

Checklist

Application

Complete loan application and program selection
Required

Note the income method (bank statement, P&L, asset depletion, DSCR, 1099).

Occupancy affidavit and any business-use notes
Required

Primary, second home, or investment. Some Non-QM products are investor-only.

Income Documentation

Alternative income package for the chosen method
Required

Bank statements, CPA P&L, asset statements, or leases/DSCR. Follow program months.

CPA letter or P&L attestation if the program requires it

P&L programs often need a CPA to attest they prepared the borrower's books.

Asset Documentation

Asset statements for required PITIA reserves
Required

All pages. Non-QM reserve overlays are often higher than conforming.

Credit

Letters of explanation for credit events and housing history
Required

Bankruptcy, foreclosure, lates, or thin credit. Include dates and resolution.

Property Documentation

Purchase contract or refinance docs and insurance
Required

Appraisal is lender-ordered. Unique properties may need extra valuation.

Identity

Government-issued photo ID (and visa/ITIN docs if applicable)
Required

Foreign-national programs add passport, visa, and foreign credit items.