←Home/Templates/Legal/Estate Planning/Beneficiary Designation Review Checklist

Beneficiary Designation Review Checklist

Estate Planning Attorney and Client Resource

Review beneficiary designations so retirement accounts, life insurance, and payable-on-death assets pass as intended. Inventory IRAs and 401(k)s, life insurance, annuities, transfer-on-death deeds or brokerage POD/TOD registrations, HSAs, and any charity or trust named as beneficiary, then confirm primary and contingent names, Social Security numbers or EINs, and whether a trust or minor is named correctly. Designations usually override a will. This is not legal or tax advice; plan-document rules and required-minimum-distribution consequences differ—confirm current plan forms and counsel's recommendations before you change a designation.
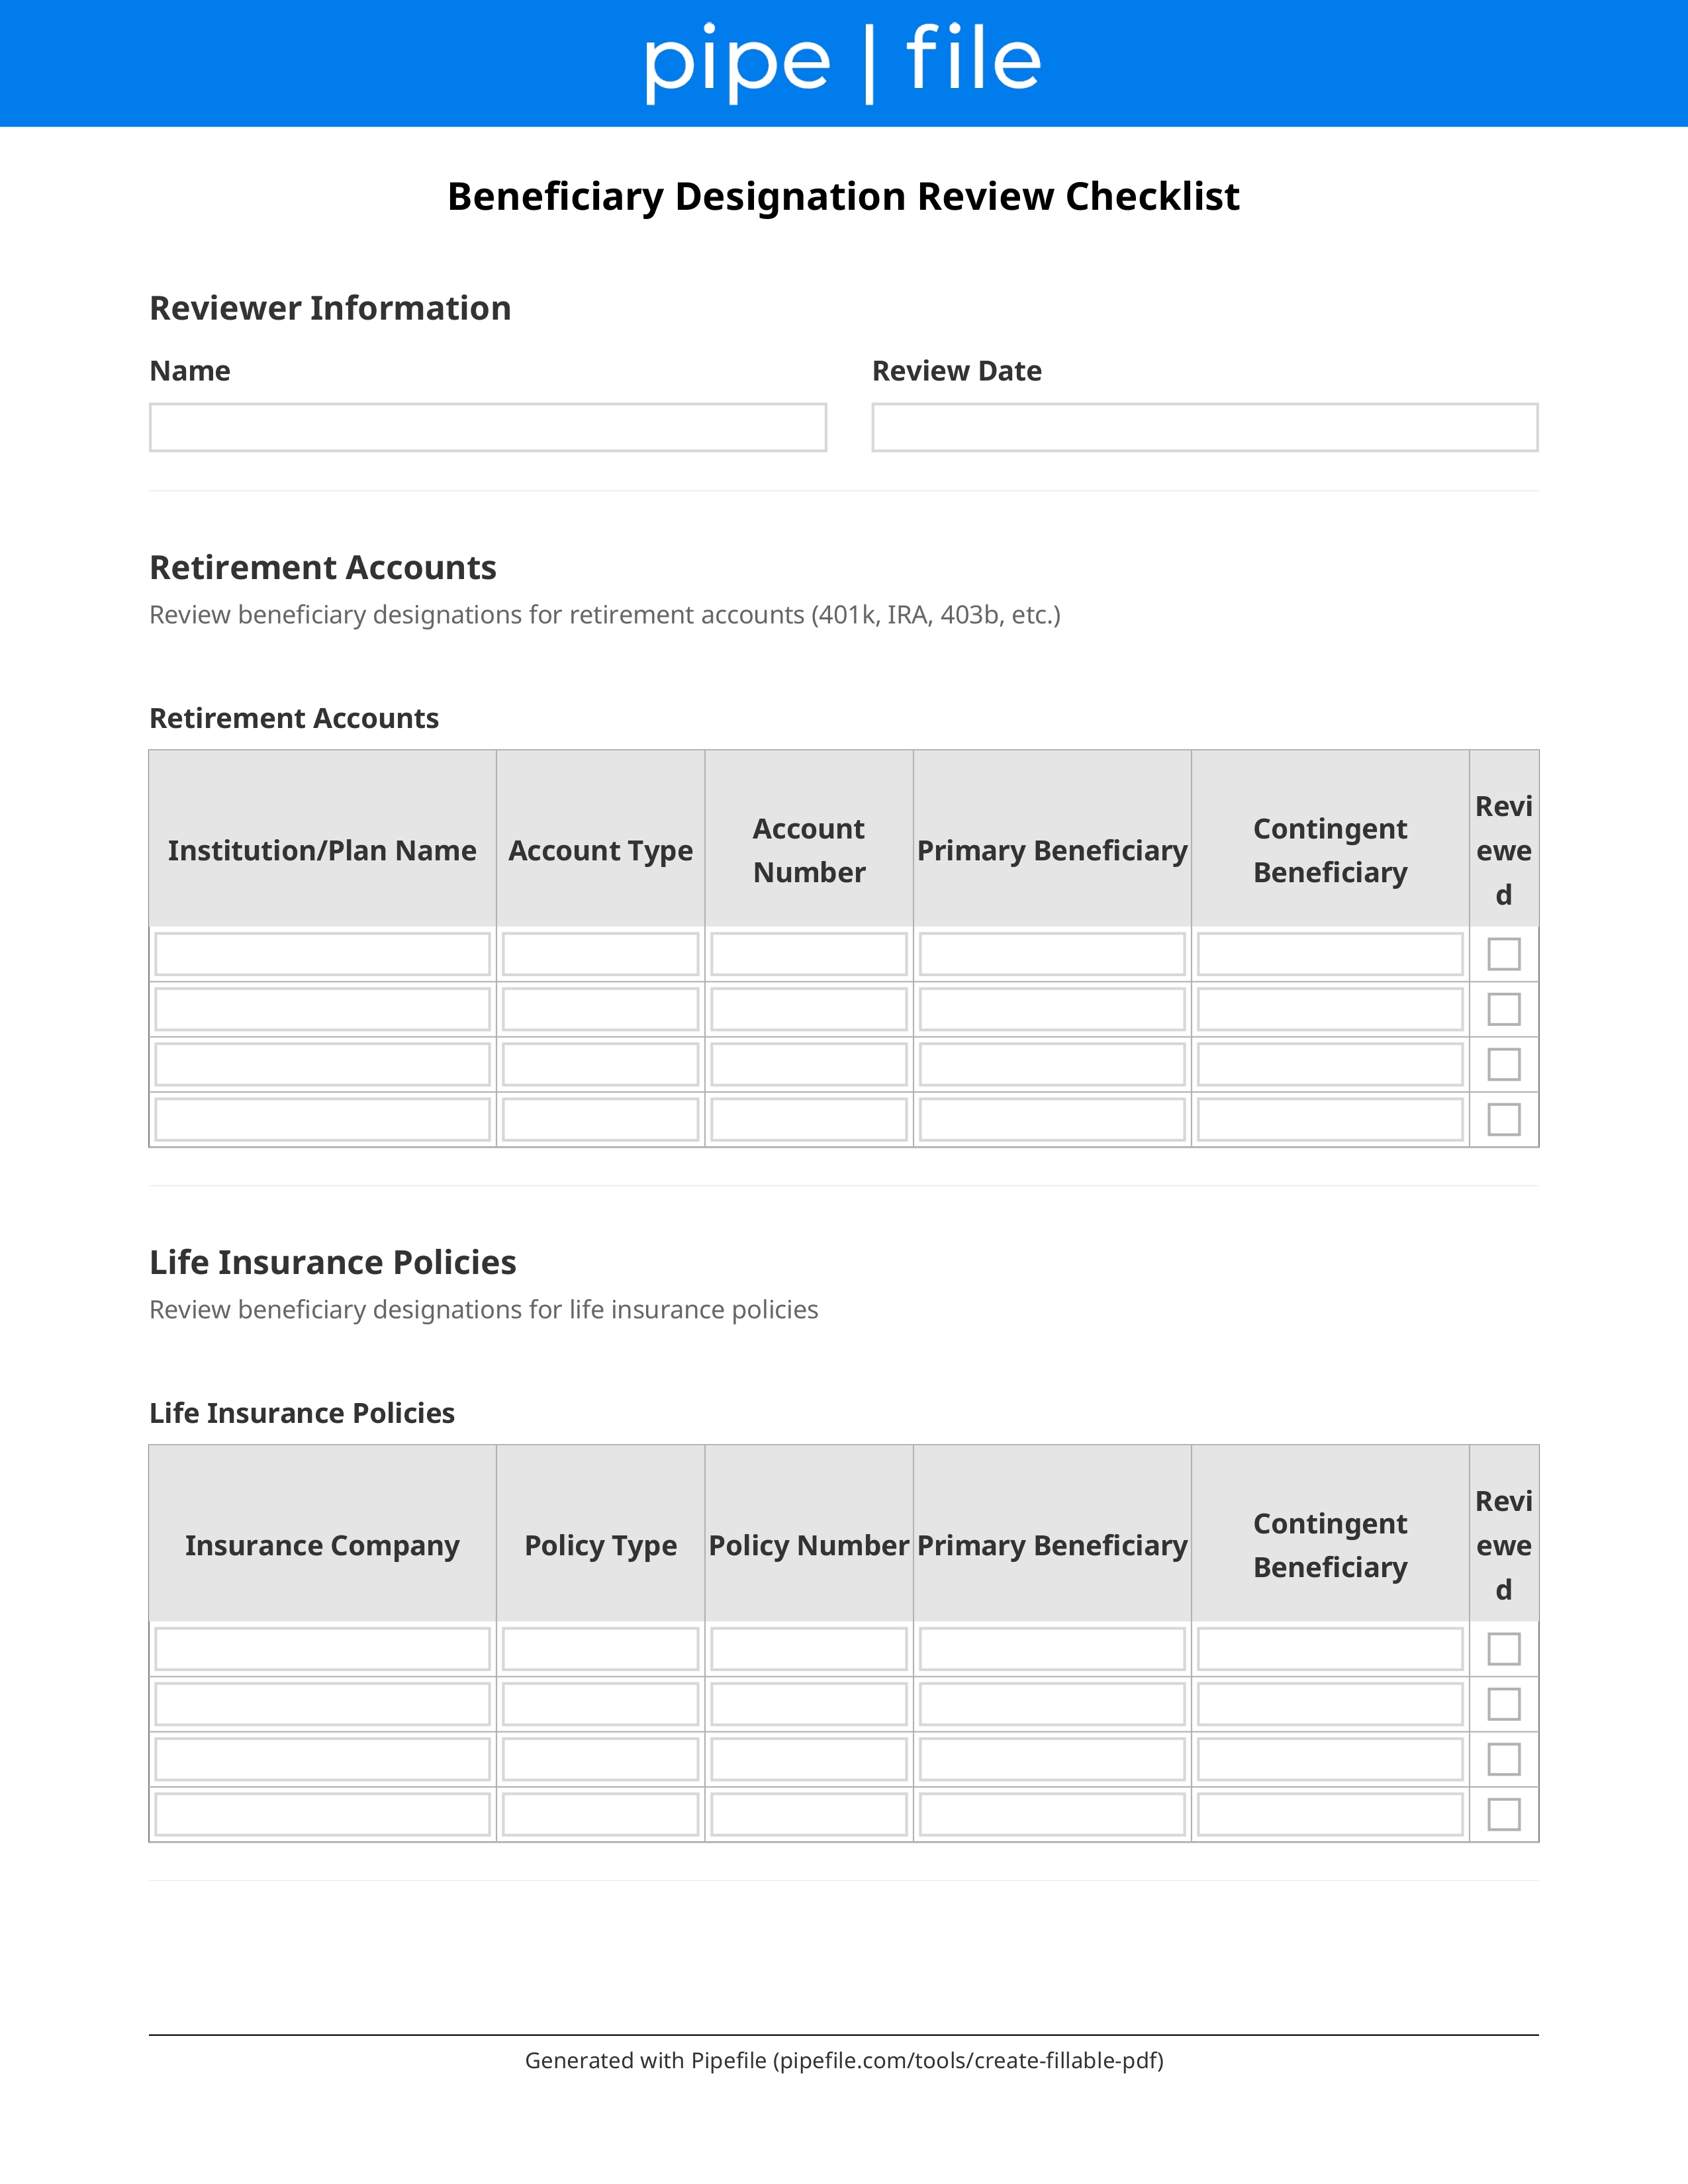
Beneficiary Designation Review Checklist form template preview

Key Benefits

Inventory every asset that passes by designation
Confirm primary and contingent beneficiaries are current
Flag ex-spouses, deceased persons, or missing contingents
Note accounts that should name a trust instead of individuals
Collect plan forms so changes can actually be filed
Keep designations aligned with the will or trust

Common Use Cases

Estate planning attorneys reviewing a new client's assetsClients updating forms after marriage, divorce, or a birthTrust funding work that must match beneficiary formsExecutors discovering outdated designations after deathFinancial advisors collecting signed plan packetsCharitable planned-giving officers confirming a charity is named correctly

Frequently Asked Questions

Why can a beneficiary form override my will?
Retirement plans, life insurance, and POD/TOD accounts pass by contract to the named beneficiary. The will does not control those assets unless the estate is the beneficiary. An outdated form is one of the most common estate-planning failures.
Should I name my living trust as beneficiary?
Sometimes, especially for minor children or blended families, but retirement accounts named to a trust have tax-timing rules. Do not change a 401(k) or IRA beneficiary to a trust without counsel and a tax advisor reviewing the trust language.
What if my plan still lists an ex-spouse?
Federal retirement-plan rules and many insurance contracts still pay the named person until you file a new form. Divorce decrees do not always rewrite the plan. Get the current form from the administrator and file an update.
Is this checklist legal advice?
No. Plan documents, ERISA, and state insurance rules control. Use the list to gather forms, then have counsel confirm names, contingents, and tax consequences.

Checklist

Retirement

IRA, 401(k), 403(b), and pension beneficiary confirmation statements
Required

Request a current designation printout from each custodian, not only the original enrollment form.

Insurance

Life insurance and annuity beneficiary pages
Required

Include employer group life and old policies in a drawer. Check contingent as well as primary.

Payable on Death

Bank POD and brokerage TOD registration forms
Required

List each account number and the named person or trust. Joint accounts may already pass by survivorship.

Other Accounts

HSA and education-savings beneficiary designations

Often overlooked. Confirm the plan allows the person you intend.

Special Beneficiaries

Trust or charity named as beneficiary, with correct legal name and EIN

Use the trust's full name and date. Charities need the legal name on the determination letter.

Review

Notes on marriage, divorce, births, deaths, or moves since the last form
Required

These events are the usual reason a form is stale. Pull the decree or new trust if relevant.

Filing

Blank official change forms from each custodian, ready to sign
Required

A letter to the advisor is not enough. The plan's own form must be accepted.

Alignment

Side-by-side note comparing designations to the will or trust distribution scheme
Required

List any intentional difference (for example, a charity on one IRA only) so it is not 'fixed' by accident.