Financial Audit Document Checklist
Controller and CPA Resource
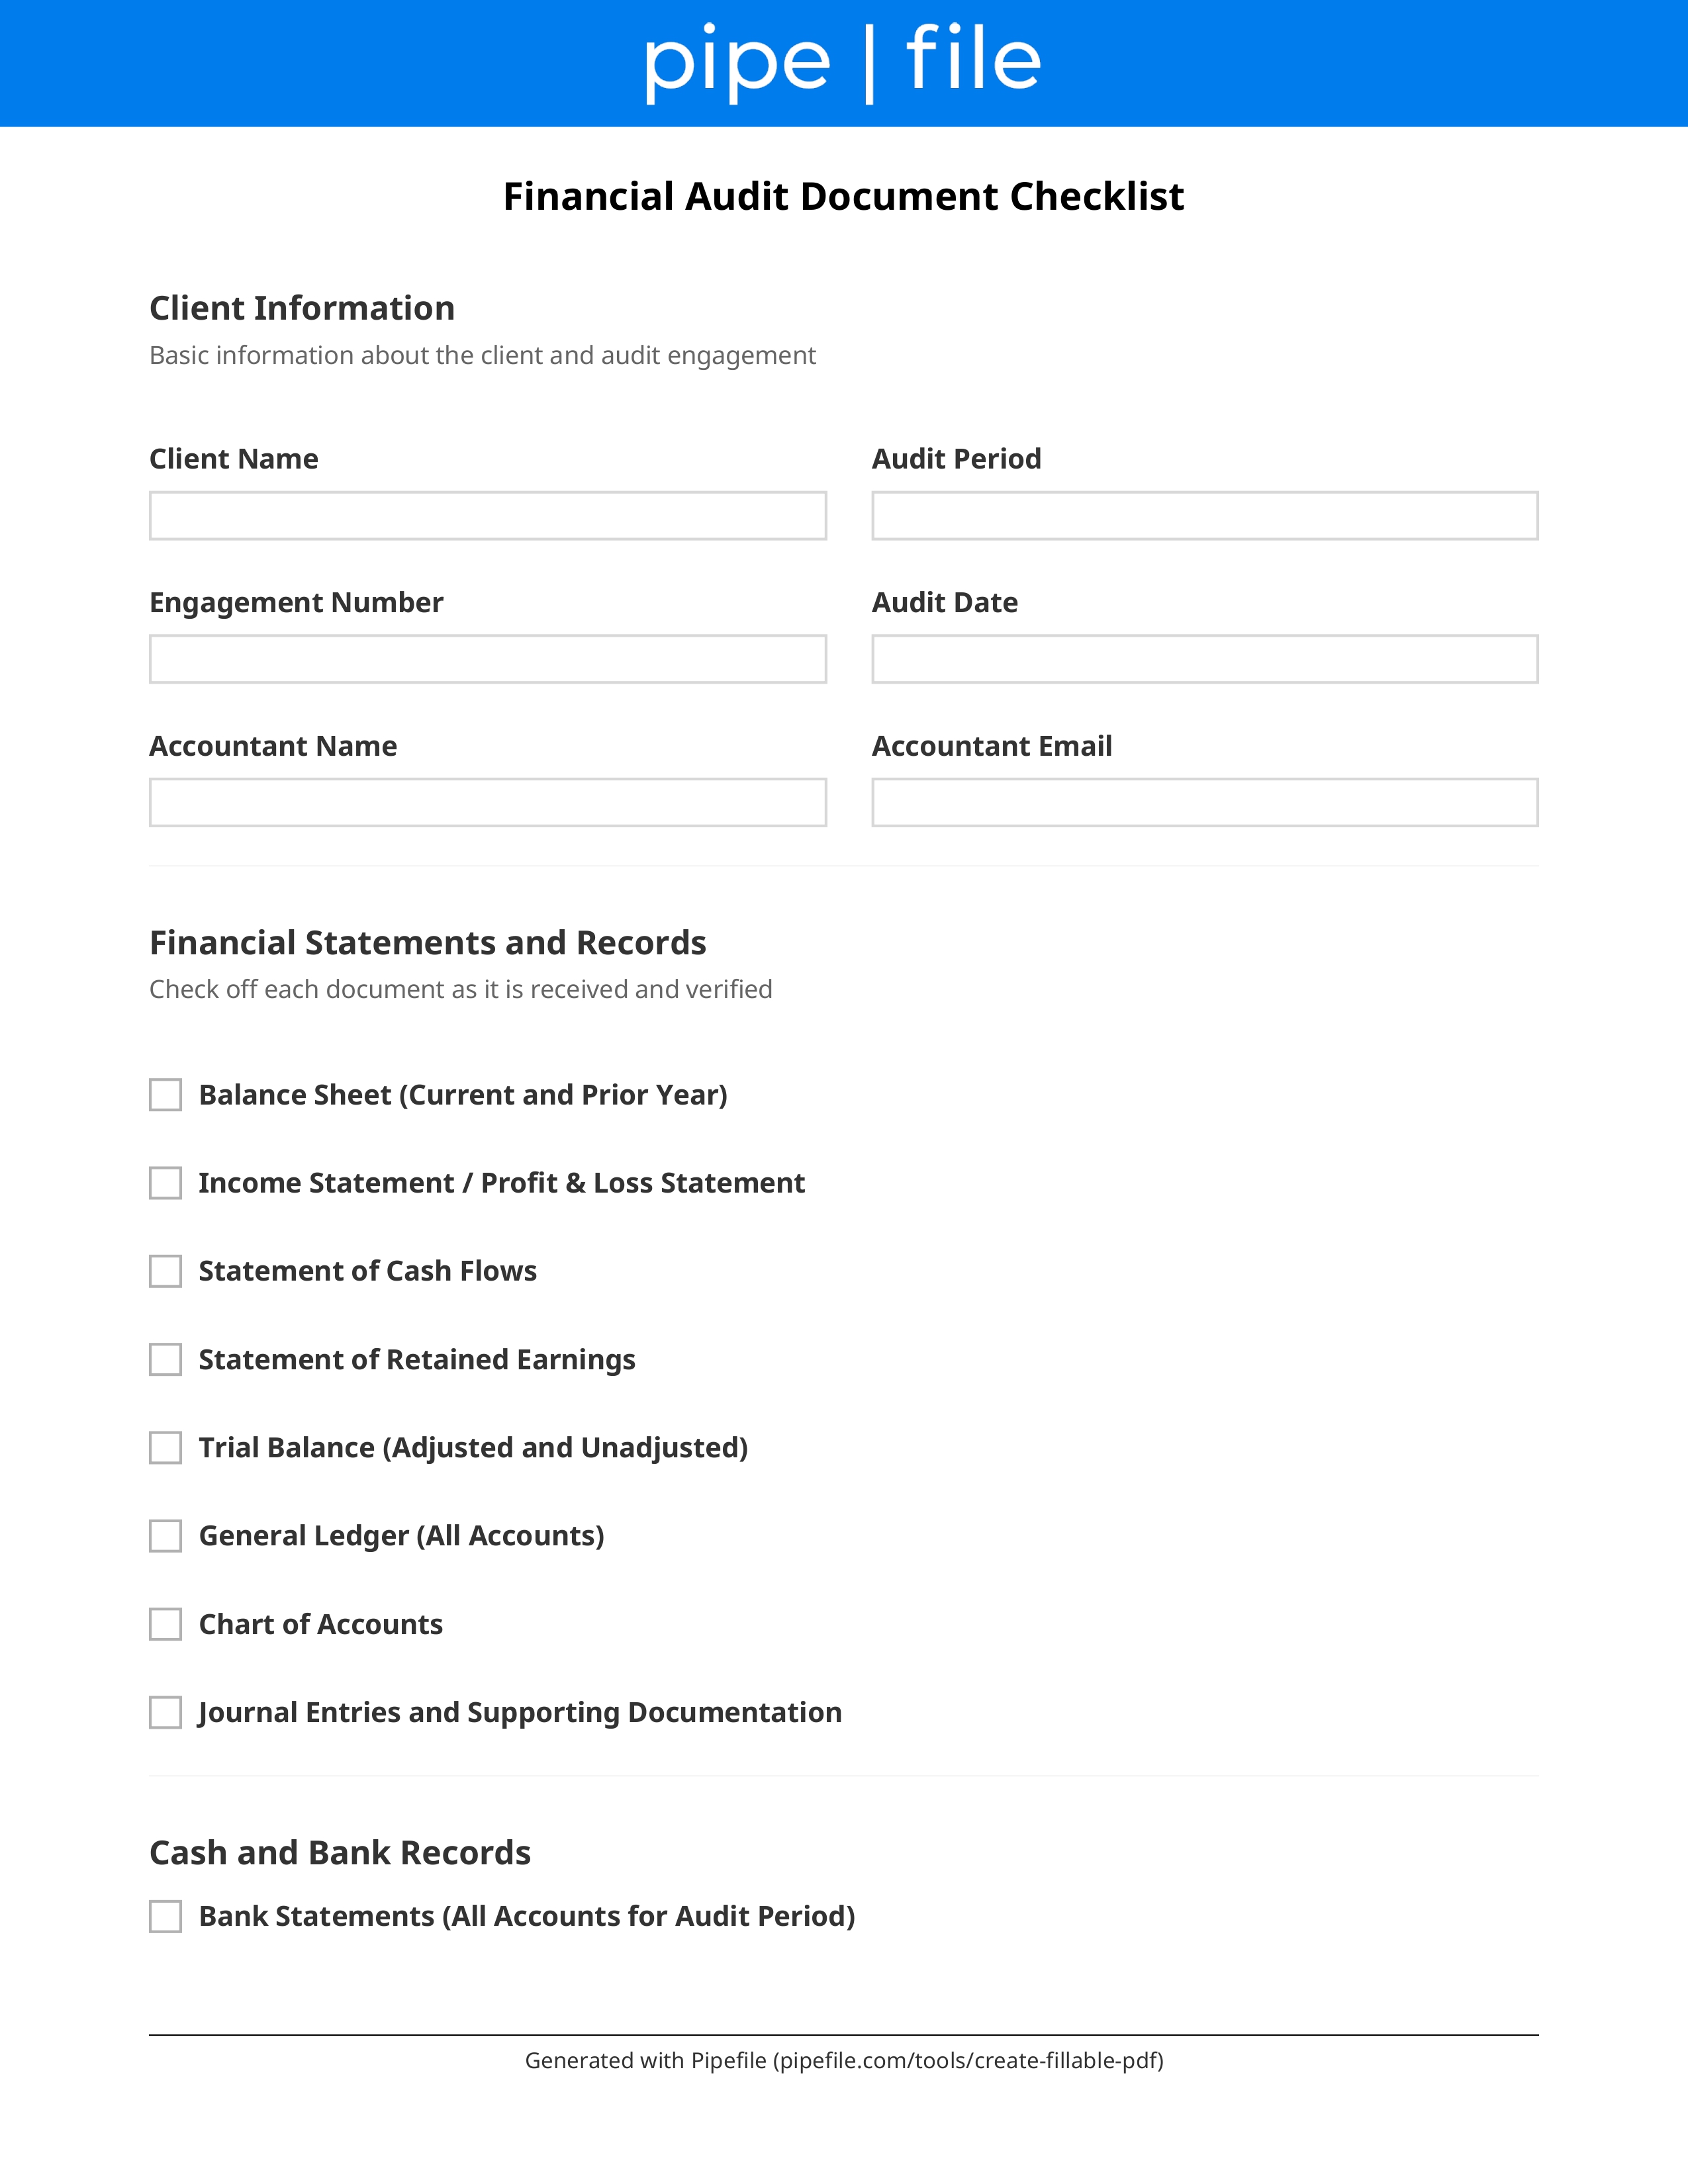
Prepare for a financial statement audit with our document checklist. For controllers, CFOs, CPAs, and nonprofit or private-company finance teams. Assemble trial balances, bank reconciliations, revenue support, debt agreements, board minutes, and policy documentation so fieldwork starts clean and PBC (prepared by client) lists stay on track. Adapt to your auditor’s engagement letter and industry. Not a substitute for audit standards or engagement-specific requests.
Key Benefits
Common Use Cases
Frequently Asked Questions
What is a PBC list?
When should we start gathering audit documents?
Do we need the same package every year?
Who should own the checklist internally?
Checklist
Financial Records
Tie to draft statements. Include consolidating entries if multi-entity.
Cash
Include outstanding checks, deposits in transit, and restricted cash support.
Receivables & Payables
Auditors often test cut-off and existence with subsequent cash activity.
Revenue
Include significant contracts, deferred revenue rollforwards, and ASC 606 memos if applicable.
Assets
Provide if material. Include depreciation and impairment support.
Liabilities
Include amendments, guarantees, and related-party notes.
Governance
Auditors review for subsequent events, commitments, and litigation.
Coordinate counsel early—legal letters often gate report issuance.
Controls
Especially important for first-year audits or control testing engagements.