←Home/Templates/Insurance/General Liability Insurance Checklist: Application Requirements

General Liability Insurance Checklist: Application Requirements

Business Owner and Commercial Broker Resource

Submit a commercial general liability (CGL) account with a document checklist for owners, risk managers, and brokers. Collect the GL application, classification and exposure worksheets (payroll, sales, or units), currently valued liability loss runs, location schedule, and customer contracts that require additional-insured or primary wording. Classification mistakes and missing loss runs are the usual quote delays. Not insurance advice; CGL forms and exclusions vary—confirm current applications and endorsements with a licensed broker.
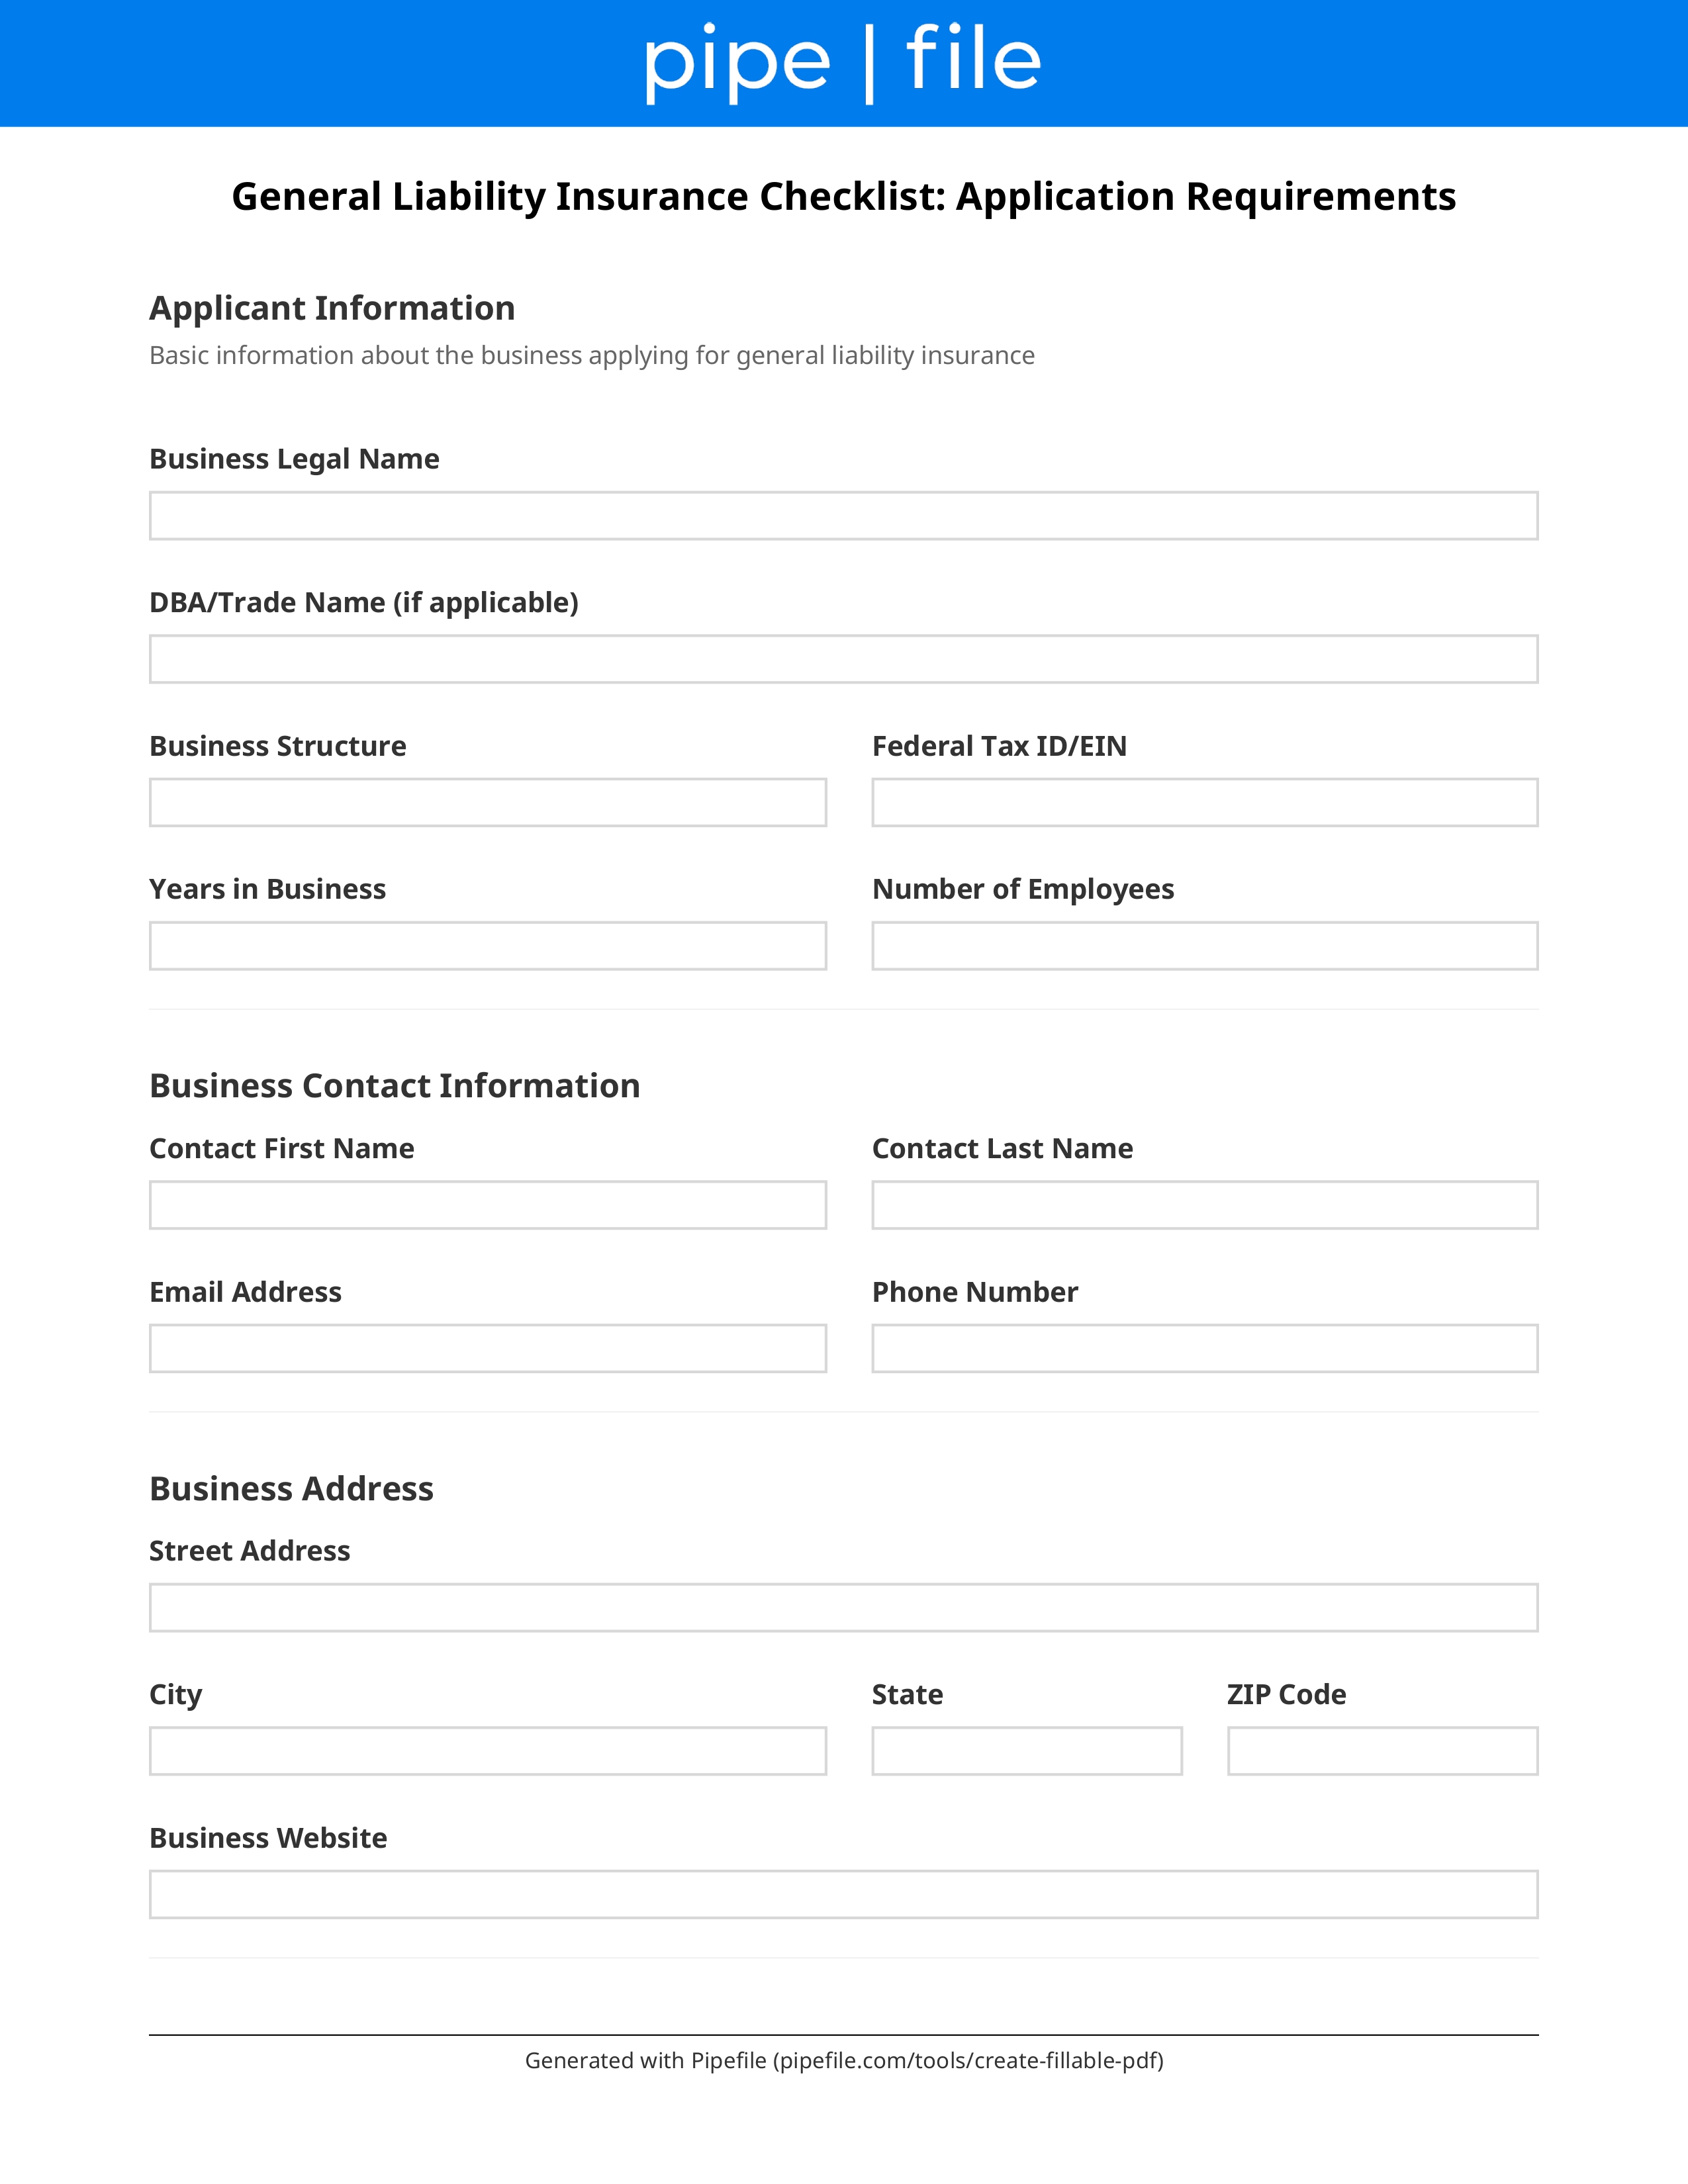
General Liability Insurance Checklist: Application Requirements form template preview

Key Benefits

Complete the current GL application and class codes
Document the rating basis: sales, payroll, or units
Order currently valued liability loss runs
List locations, additional named insureds, and DBAs
Attach contracts that mandate AI or waiver wording
Compare expiring limits and endorsements

Common Use Cases

Contractors placing or renewing CGLLandlords and lessors-risk submissionsProduct sellers needing products-completed opsRetail and restaurant package GL sectionsBrokers building a middle-market submissionBid packages that specify GL limits

Frequently Asked Questions

What does a CGL policy typically address?
A commercial general liability policy generally addresses certain third-party bodily injury, property damage, and personal/advertising injury claims arising from your operations, subject to the form and exclusions. It is not a substitute for professional, auto, or workers-compensation coverage.
Why do underwriters care about classification?
ISO or carrier class codes drive rate and exclusions. Misclassifying a contractor as a less hazardous class can void expected coverage or cause audit surprises. Describe operations in plain language on the application.
What contracts should we attach?
Customer, GC, and landlord agreements that require additional insured, primary and noncontributory, waiver of subrogation, or specific limits. Underwriters need those exhibits to quote the right endorsements.
Is this insurance advice?
No. Coverage is defined by the policy. Confirm current forms, audits, and exclusions with a licensed broker for your operations and states.

Checklist

Application

Signed CGL or package application with operations narrative
Required

Legal names, FEIN, and years in business.

Exposures

Rating exposures: payroll, sales, units, or area by class
Required

Split by state if multi-state.

Claims

Currently valued GL loss runs (typically 3–5 years)
Required

Include currently valued date stamps.

Named Insureds

Location schedule and additional named insureds or DBAs
Required

Who must appear on the policy.

Contracts

Insurance exhibits requiring AI, PNC, or waiver wording

Attach rather than summarize.

Products

Product list, sales by product, and warning-label samples if products risk

For manufacturers and distributors.

Subs

Subcontractor cost and whether you collect certificates

Common contractor underwriting question.

Expiring

Expiring declarations, limits, deductibles, and endorsements
Required

Compare occurrence vs claims-made if relevant.