←Home/Templates/Real Estate/Short Sale Checklist: Document Requirements

Short Sale Checklist: Document Requirements

Seller, Agent, and Loss-Mitigation Resource

Build a short-sale approval package with a document checklist for sellers, listing agents, and loss-mitigation specialists. Collect the hardship letter, financials the servicer lists, tax returns, bank statements, the listing agreement and HUD-1 or closing-cost estimate, arm’s-length affidavits, and all junior-lien contacts. Investor rules and timelines change; an incomplete package stalls approval. This is not legal, tax, or foreclosure advice. Confirm current servicer requirements and any tax consequences of forgiven debt with qualified advisors.
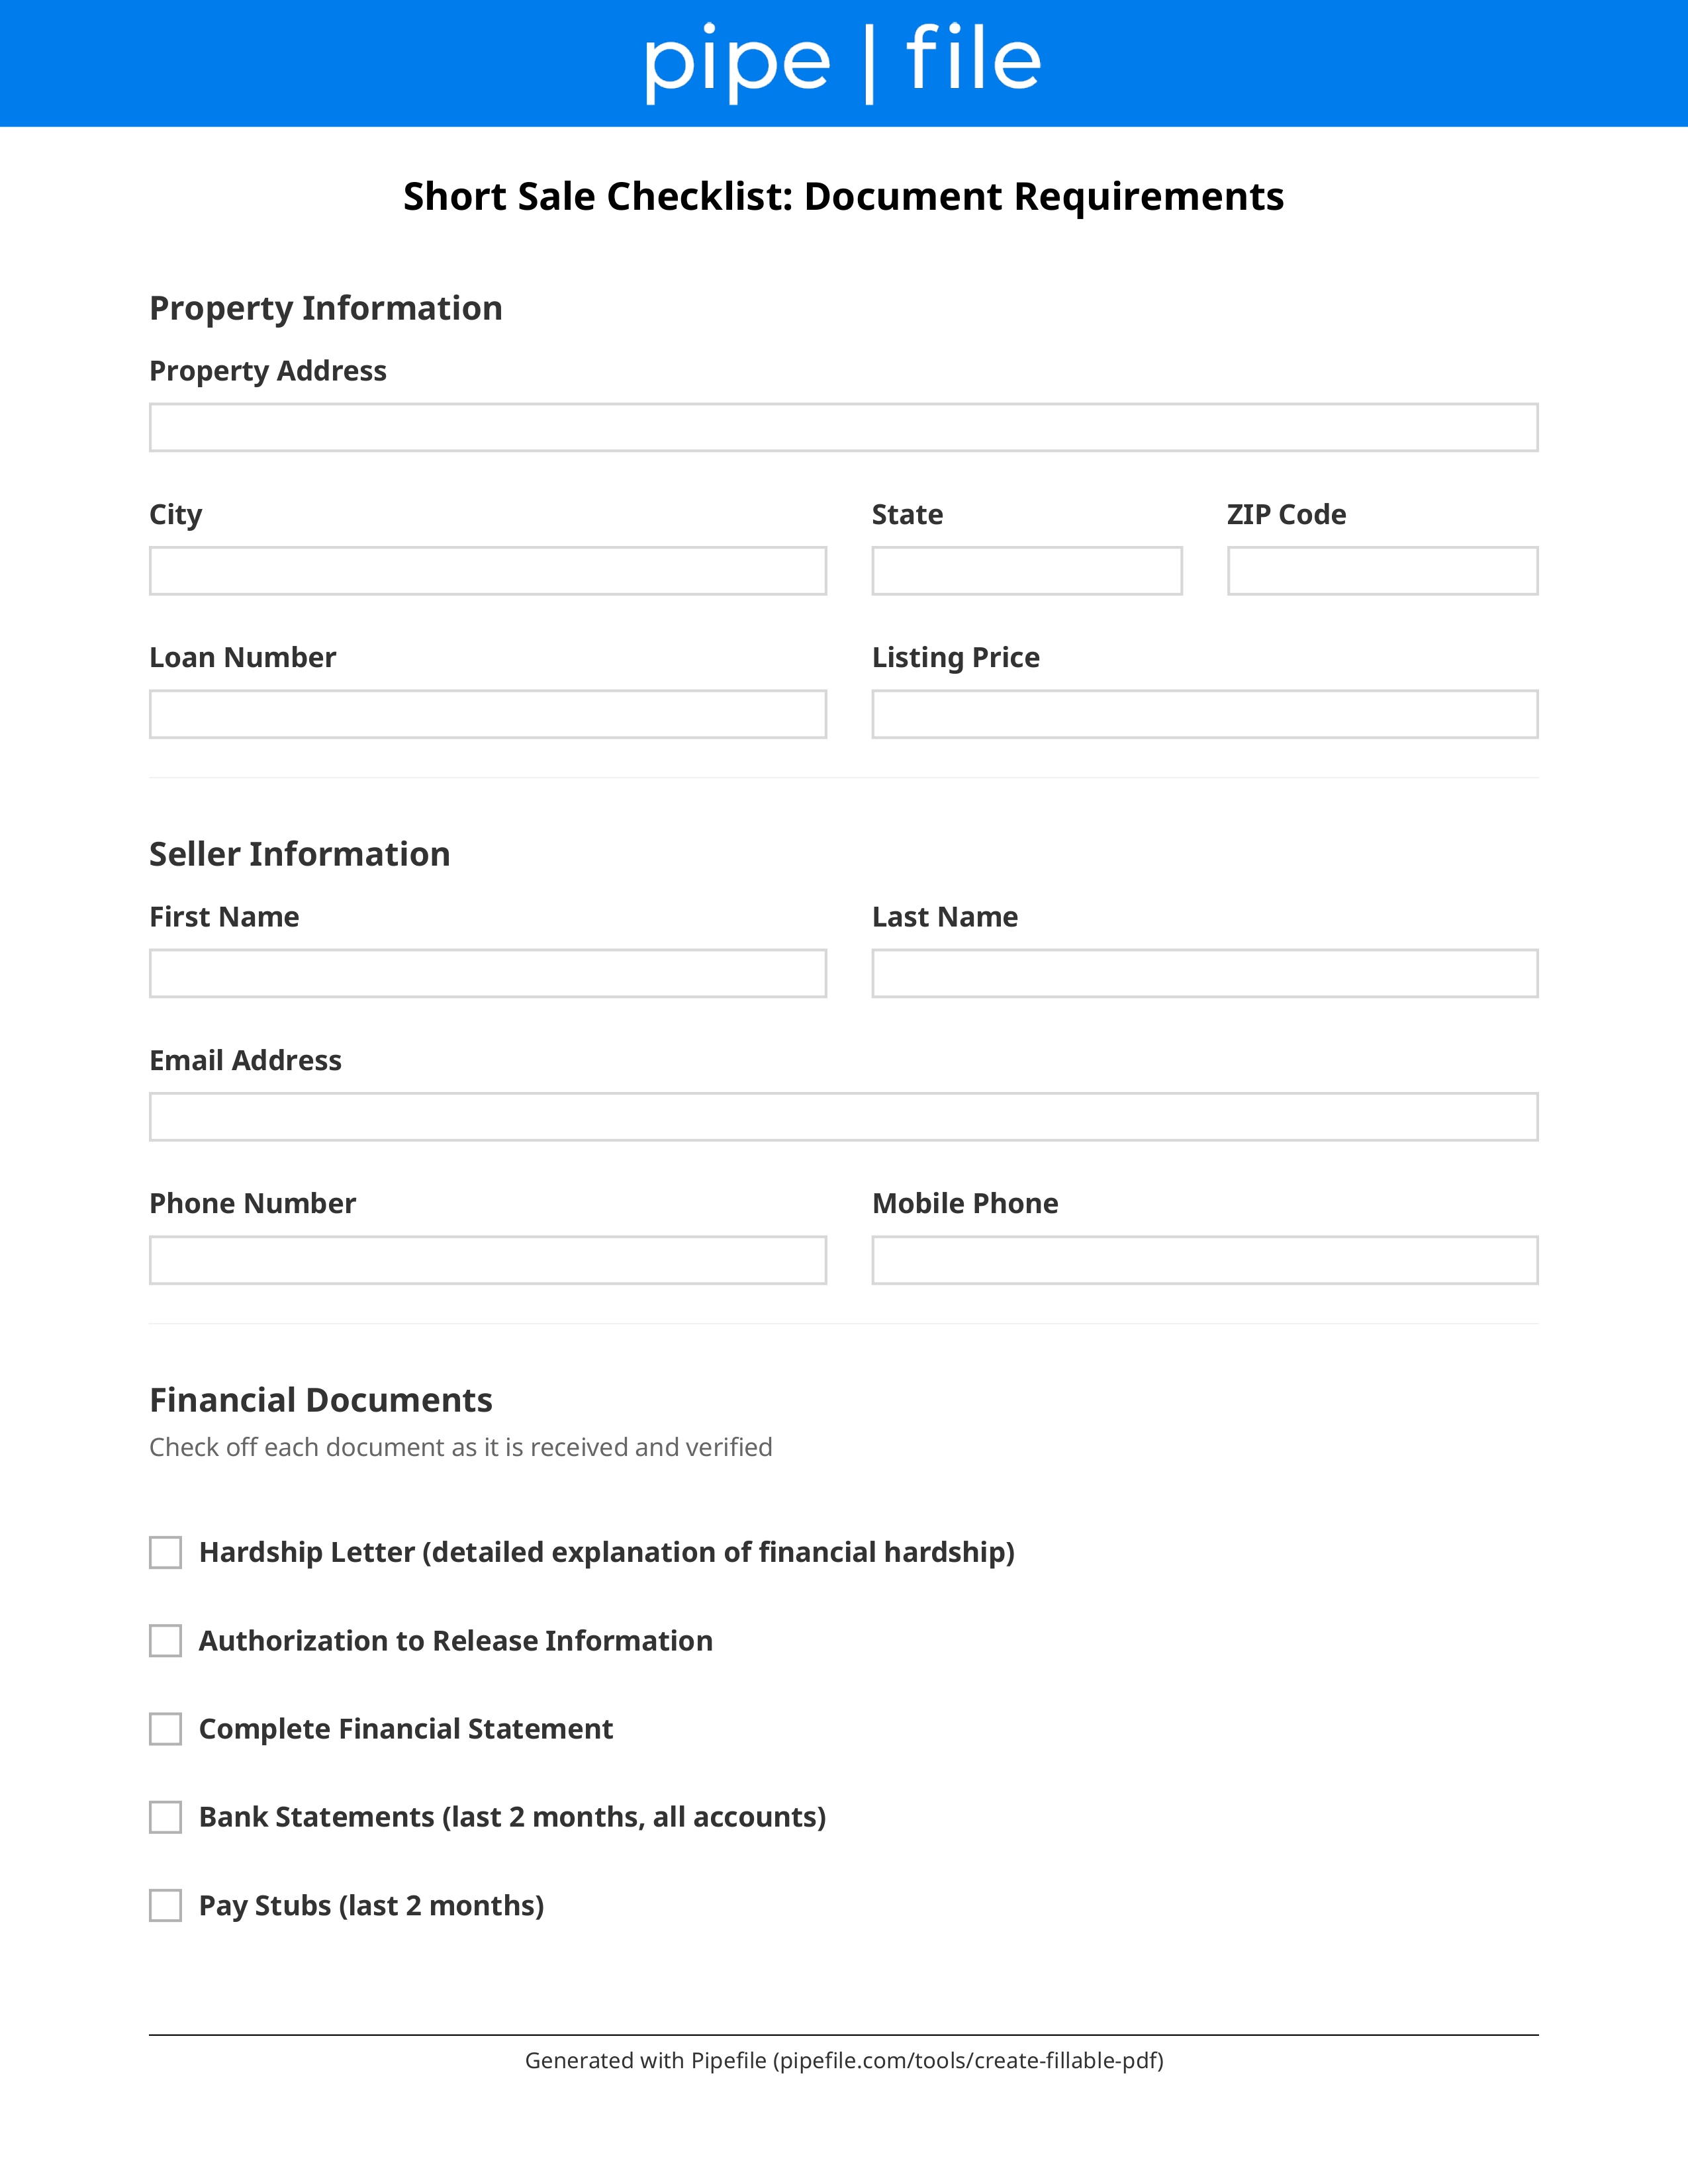
Short Sale Checklist: Document Requirements form template preview

Key Benefits

Use the servicer’s current short-sale document list
Attach a factual hardship letter and income proof
Include listing history and a realistic HUD-1 estimate
Collect junior-lien and HOA payoff contacts
File arm’s-length and occupancy affidavits if required
Track approval expiration dates before closing

Common Use Cases

Owner-occupant short sales after a hardshipAgents submitting a first complete packageCounsel coordinating junior-lien releasesInvestor sales that still need servicer approvalSecond-lien negotiations alongside the firstRe-submitting after a buyer or price change

Frequently Asked Questions

What is a short sale?
A sale where the lender agrees to accept less than the payoff to release the mortgage. Approval is discretionary and document-driven. Closing cannot happen on the purchase contract alone.
Will I owe taxes on forgiven debt?
Possibly. Canceled mortgage debt can be taxable unless an exclusion applies. This checklist does not determine tax results. Speak with a tax professional and keep the Form 1099-C if issued.
How long does approval take?
Weeks to months depending on the investor, completeness, and junior liens. Use current forms and answer conditions quickly. A sale date in a foreclosure notice may still run—coordinate with counsel.
Is this legal advice?
No. Short sales interact with foreclosure, bankruptcy, and tax rules. Confirm current servicer and state requirements with a counselor, attorney, or tax advisor.

Checklist

Hardship

Signed hardship letter and supporting event documents
Required

Job loss, divorce, medical, or other facts the investor recognizes.

Financials

Servicer financial statement, pay stubs, and bank statements
Required

All pages; follow the look-back on the current form.

Recent federal tax returns and W-2 or 1099 forms
Required

As listed by the investor.

Marketing

Listing agreement, MLS history, and comparable sales used
Required

Shows the property was marketed.

Closing

Estimated HUD-1 or closing disclosure with all costs
Required

Buyer credits and commissions must match the request.

Contract

Fully executed purchase agreement and buyer proof of funds
Required

Arm’s-length buyer unless the investor allows otherwise.

Affidavits

Arm’s-length and occupancy affidavits the servicer requires
Required

Notarize if the form says so.

Liens

Second-lien, HOA, and tax-lien payoff contacts
Required

Junior releases often delay approval.