←Home/Templates/Finance/Lending/SBA 504 Loan Checklist: Document Requirements

SBA 504 Loan Checklist: Document Requirements

CDC and Owner-Occupied SBA Lending Resource

Streamline your SBA 504 loan application with our comprehensive document checklist. For owner-occupied real estate or major equipment projects and for CDCs and banks. The 504 structure is a first-mortgage bank loan plus a CDC/SBA debenture. Gather SBA forms, project costs, appraisal items, business and personal financials, and job or public-policy narratives so the CDC can submit a complete package.
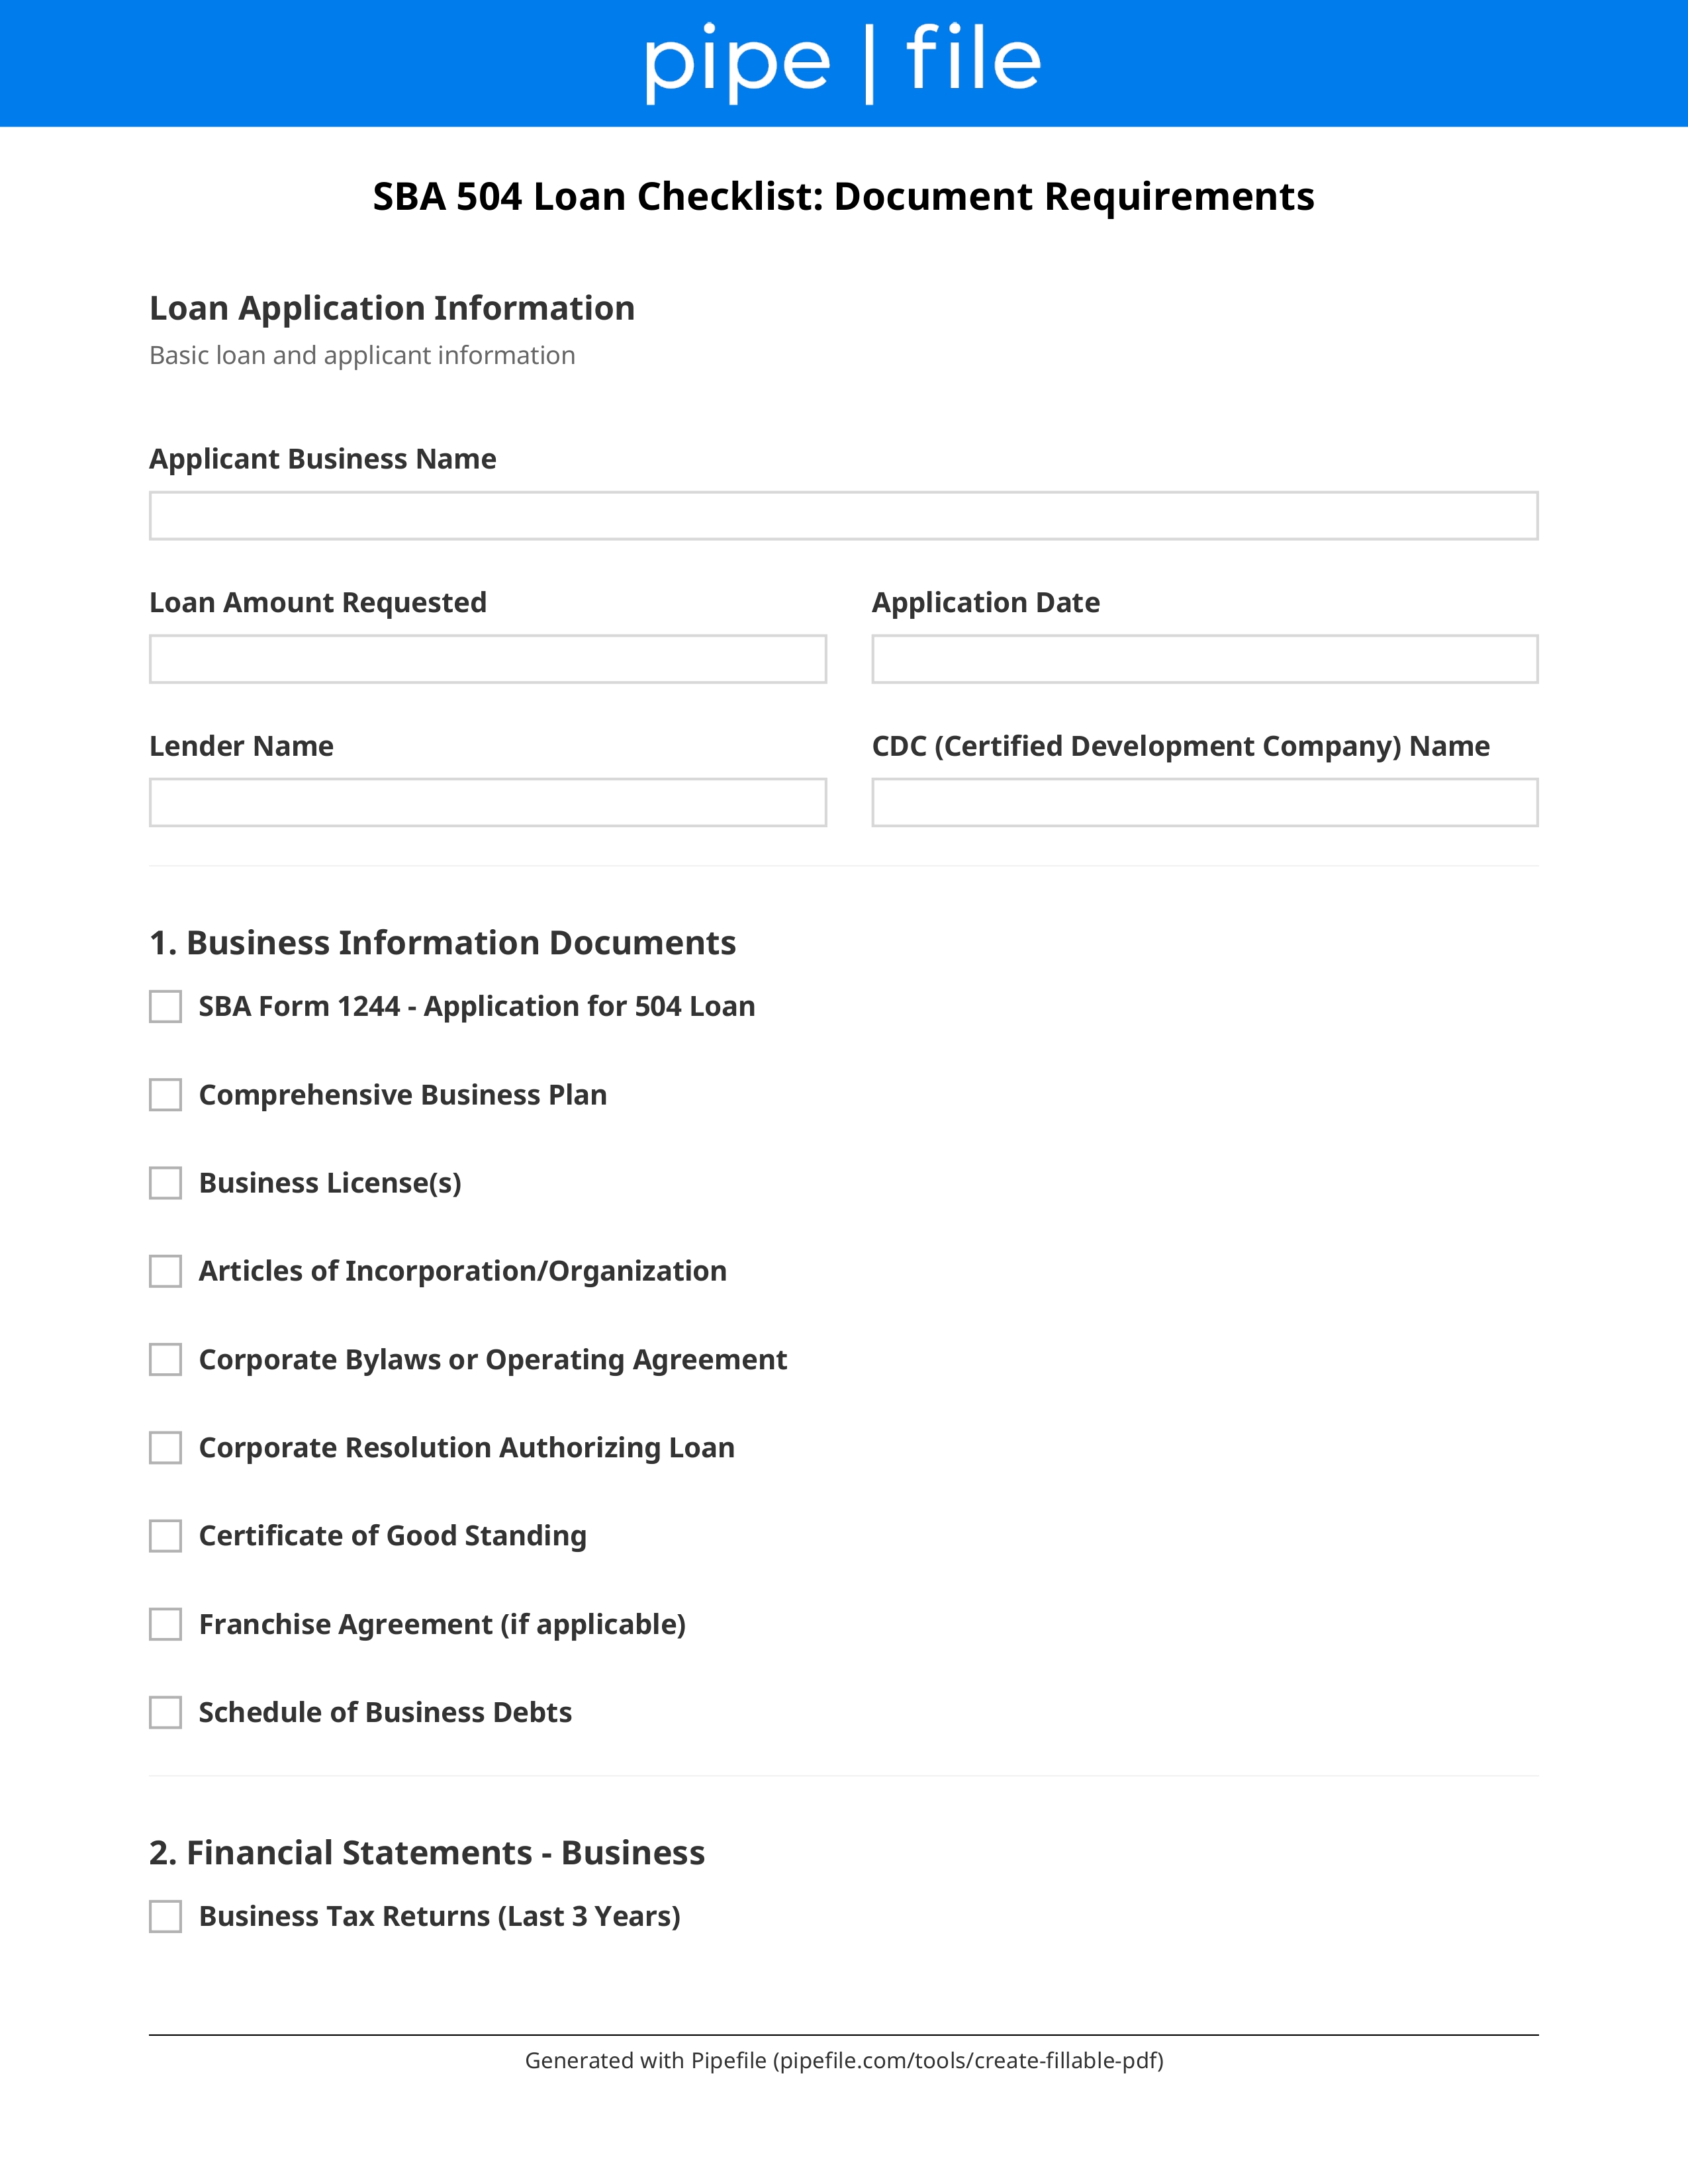
SBA 504 Loan Checklist: Document Requirements form template preview

Key Benefits

Build the three-part 504 stack (bank, CDC, borrower equity)
Gather SBA forms used on 504 projects
Document project costs, appraisal, and environmental
Prepare business and personal financials for CDC review
Support job-creation or public-policy eligibility
Professional 504 lending workflow

Common Use Cases

Owners buying or building owner-occupied commercial real estateCompanies financing heavy equipment with a 504CDCs packaging a 504 authorizationBanks originating the first-mortgage pieceBorrowers refinancing eligible 504 projects where allowedAdvisors comparing 504 vs. 7(a) for a real-estate project

Frequently Asked Questions

What is an SBA 504 loan?
SBA 504 finances owner-occupied commercial real estate and long-life equipment through a first-lien bank loan (typically 50%), a CDC/SBA debenture (typically 40%), and borrower equity (typically 10%, more for startups or special-purpose property). The CDC handles the SBA guaranty piece.
What documents does a 504 require?
SBA forms (including 1244 and personal history/financials), 2-3 years of business and personal tax returns and financials, a project cost breakdown, purchase contract or construction budget, appraisal and environmental as required, entity docs, and a jobs or public-policy narrative.
How does 504 differ from 7(a)?
7(a) is a single lender loan that can fund working capital and many uses. 504 is a structured real-estate or equipment project with a CDC partner and typically lower down payment and longer real-estate terms. You cannot use 504 for working capital or inventory.
How much equity do I need?
Standard 504 is 10% borrower equity. Startups, special-purpose properties, or both can require 15% or 20%. Equity can be cash or eligible injection. The CDC will document source of equity as carefully as the bank does.

Checklist

SBA Forms

SBA 504 application forms (including 1244 and personal history/financials)
Required

CDC provides the current packet. Each 20%+ owner and guarantor completes personal forms.

Project

Project cost breakdown and sources-and-uses (bank, CDC, equity)
Required

Purchase, construction, equipment, soft costs, and eligible fees. Must foot to the structure.

Purchase contract or construction plans, budget, and contractor info
Required

Owner-occupancy must be met. Construction 504s add builder credentials.

Financial Documentation

Business tax returns and financials (2-3 years plus YTD)
Required

P&L, balance sheet, debt schedule. Interim must be recent.

Personal tax returns and Form 413 for each owner 20%+ and guarantor
Required

Supports repayment ability and equity injection source.

Business Documentation

Entity documents, ownership, and affiliates list
Required

Articles, operating agreement, EIN, and SBA affiliate disclosure.

Collateral

Appraisal and environmental reports as required for the project
Required

CDC and bank order or accept per SOP. Phase I common on commercial real estate.

Eligibility

Job creation/retention or public-policy eligibility narrative
Required

504 requires an economic-development purpose. CDC will help frame it.

Application

Credit authorizations for business and guarantors
Required

Bank and CDC will both pull credit.