Reverse Mortgage Checklist (HECM)
HECM and Senior Home-Equity Resource
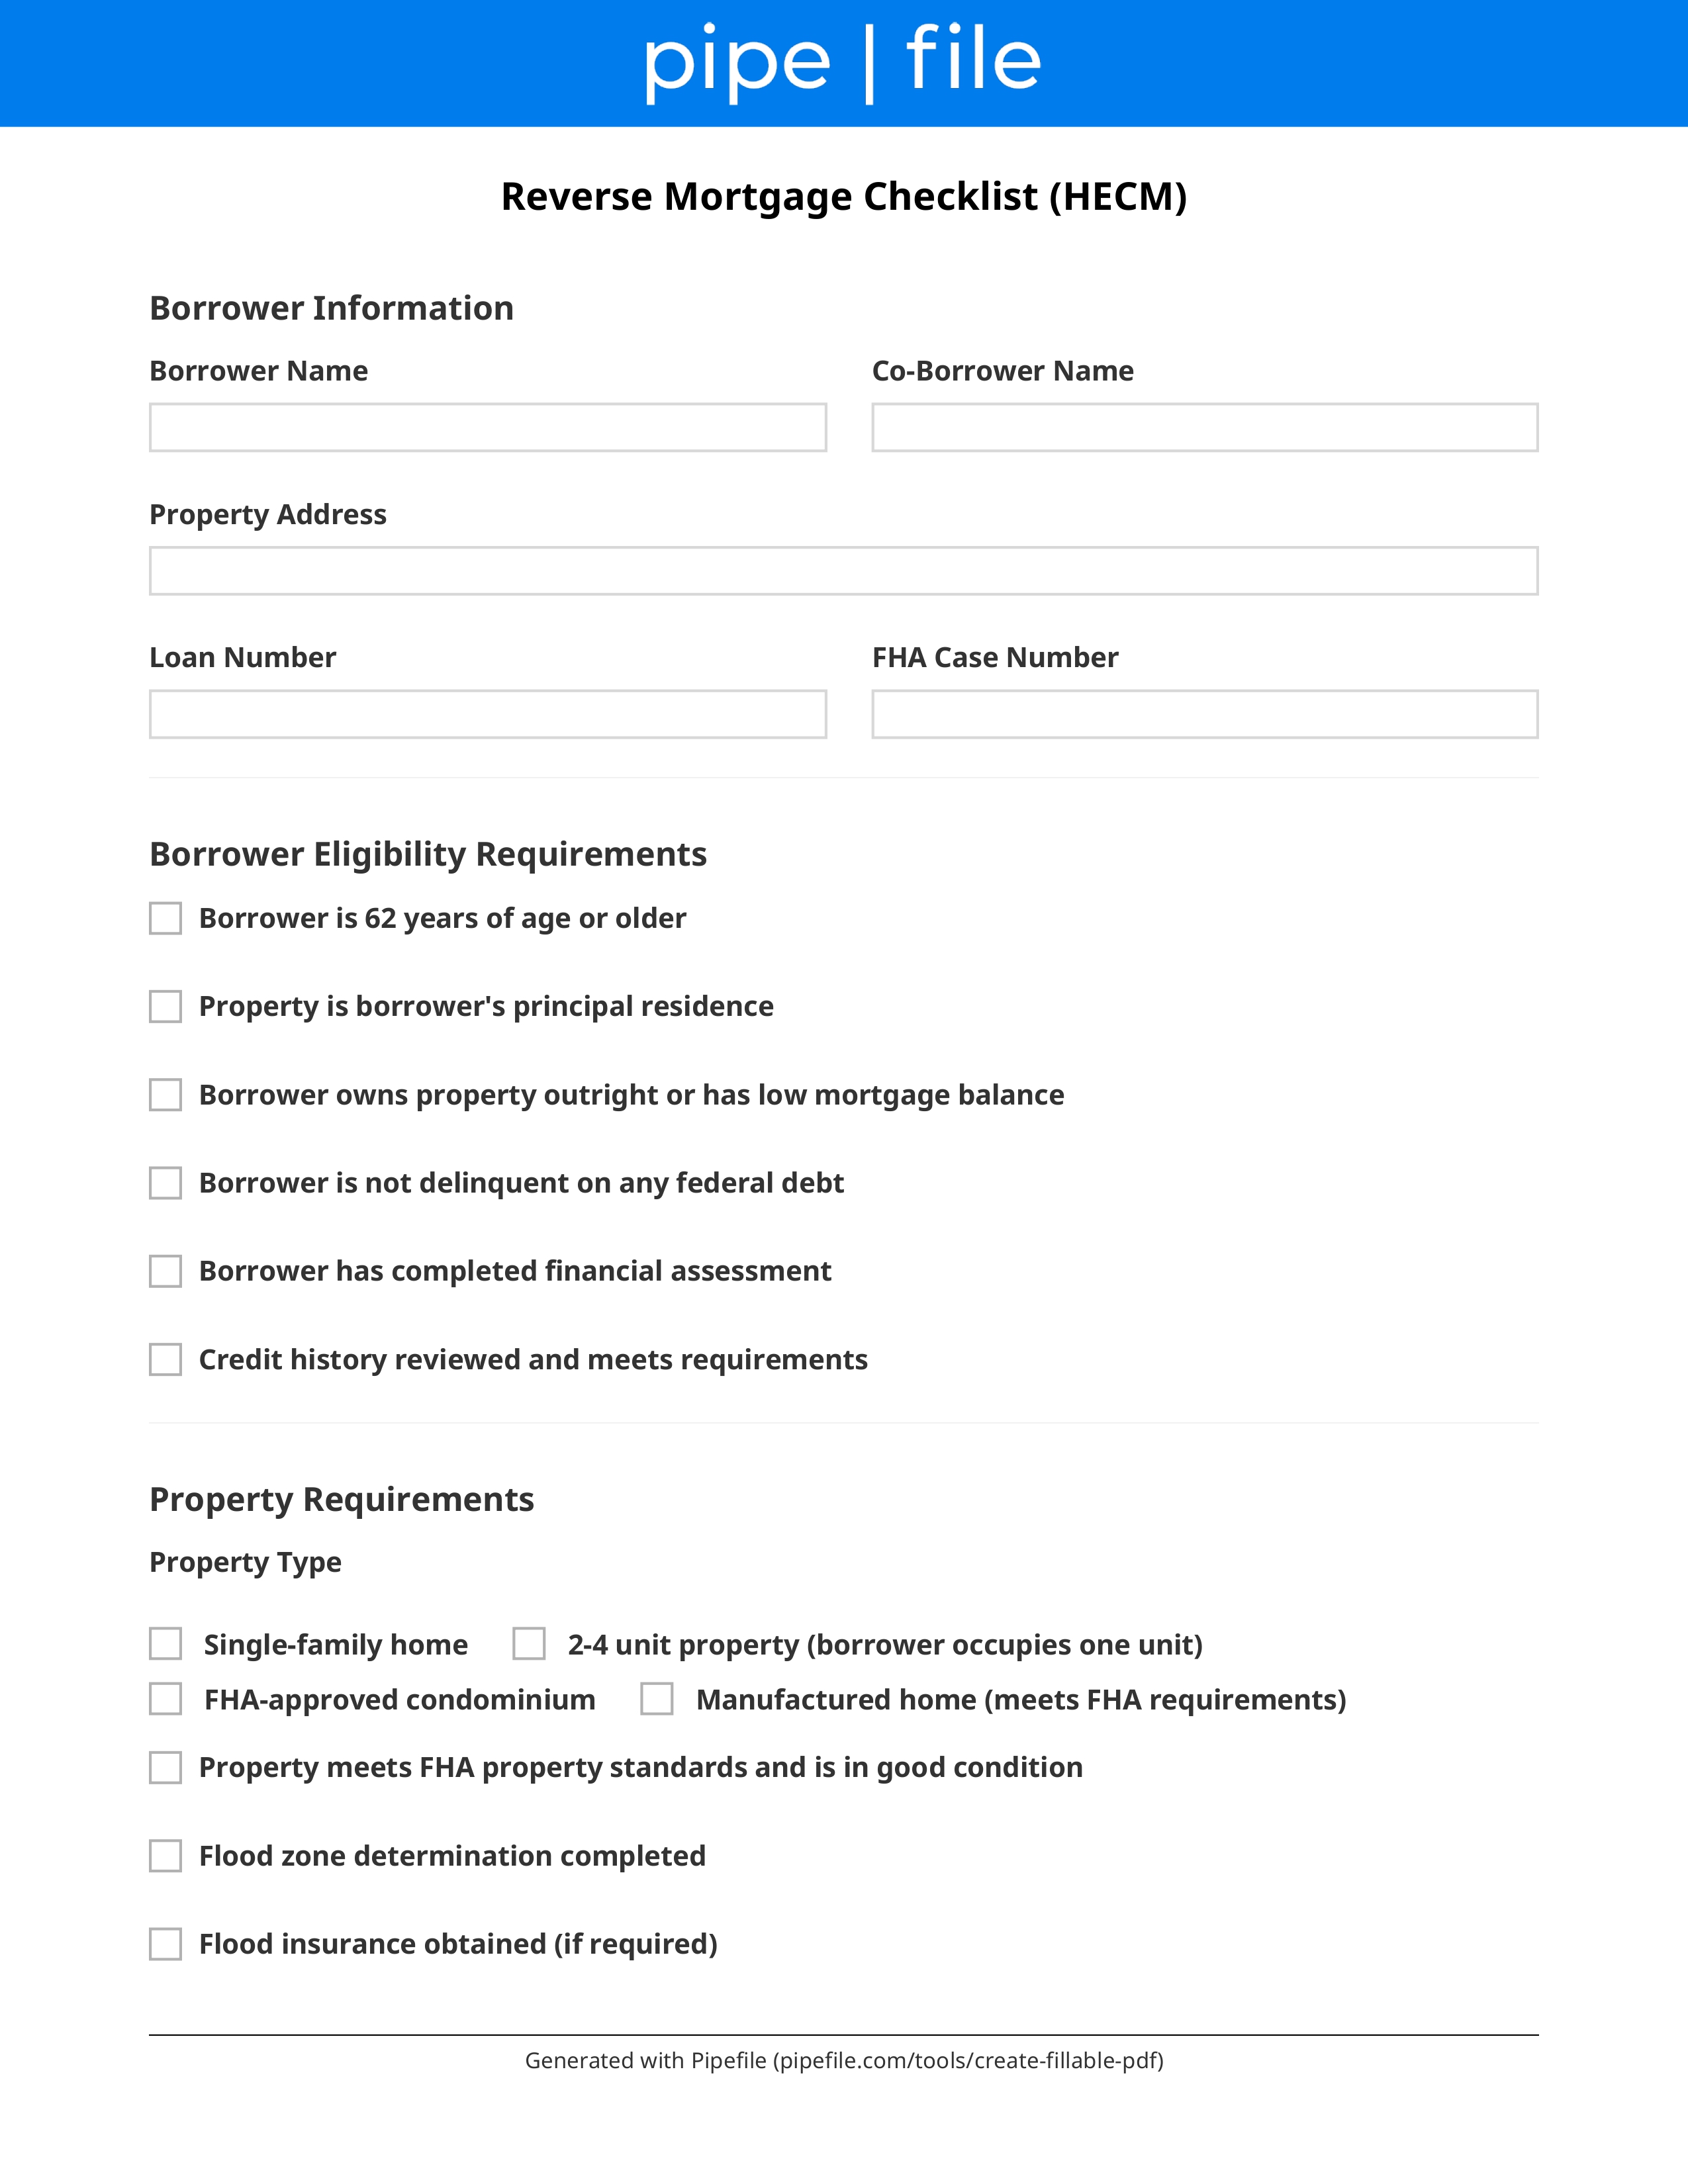
Streamline your HECM reverse mortgage application with our comprehensive document checklist. For homeowners 62 and older, counselors, and HECM lenders. Collect the HUD counseling certificate, age and identity documents, property ownership and payoff, financial-assessment items (income, taxes, insurance, HOA), and occupancy so the lender can underwrite proceeds and residual-life obligations.
Key Benefits
Common Use Cases
Frequently Asked Questions
What is a HECM reverse mortgage?
What documents are required for a HECM?
Is HUD counseling required?
What is the HECM financial assessment?
Checklist
Counseling
Required before the lender can originate. Watch the certificate expiration date.
Application
All borrowers must be 62+. Non-borrowing spouse rules if applicable.
Trusts and life estates need extra legal review before closing.
Identity
Driver's license, passport, or birth certificate as the lender specifies.
Property Documentation
Must occupy as principal residence. Liens affect principal limit.
Delinquent property charges drive set-asides or denial.
Financial Assessment
Pay or benefit statements, tax transcripts if required, and credit authorization.
Valuation
Establishes maximum claim amount and principal limit.