←Home/Templates/Finance/Accounting/Form 1120 Checklist: Corporate Tax Return

Form 1120 Checklist: Corporate Tax Return

CPA and Corporate Tax Resource

Prepare Form 1120 (U.S. Corporation Income Tax Return) with our document checklist. For CPAs, corporate controllers, and C-corporation finance teams. Gather financial statements, M-1/M-3 reconciling items, fixed assets, officer compensation, and estimated tax payments so the corporate return is complete and supportable. Confirm current IRS schedules. Not tax advice.
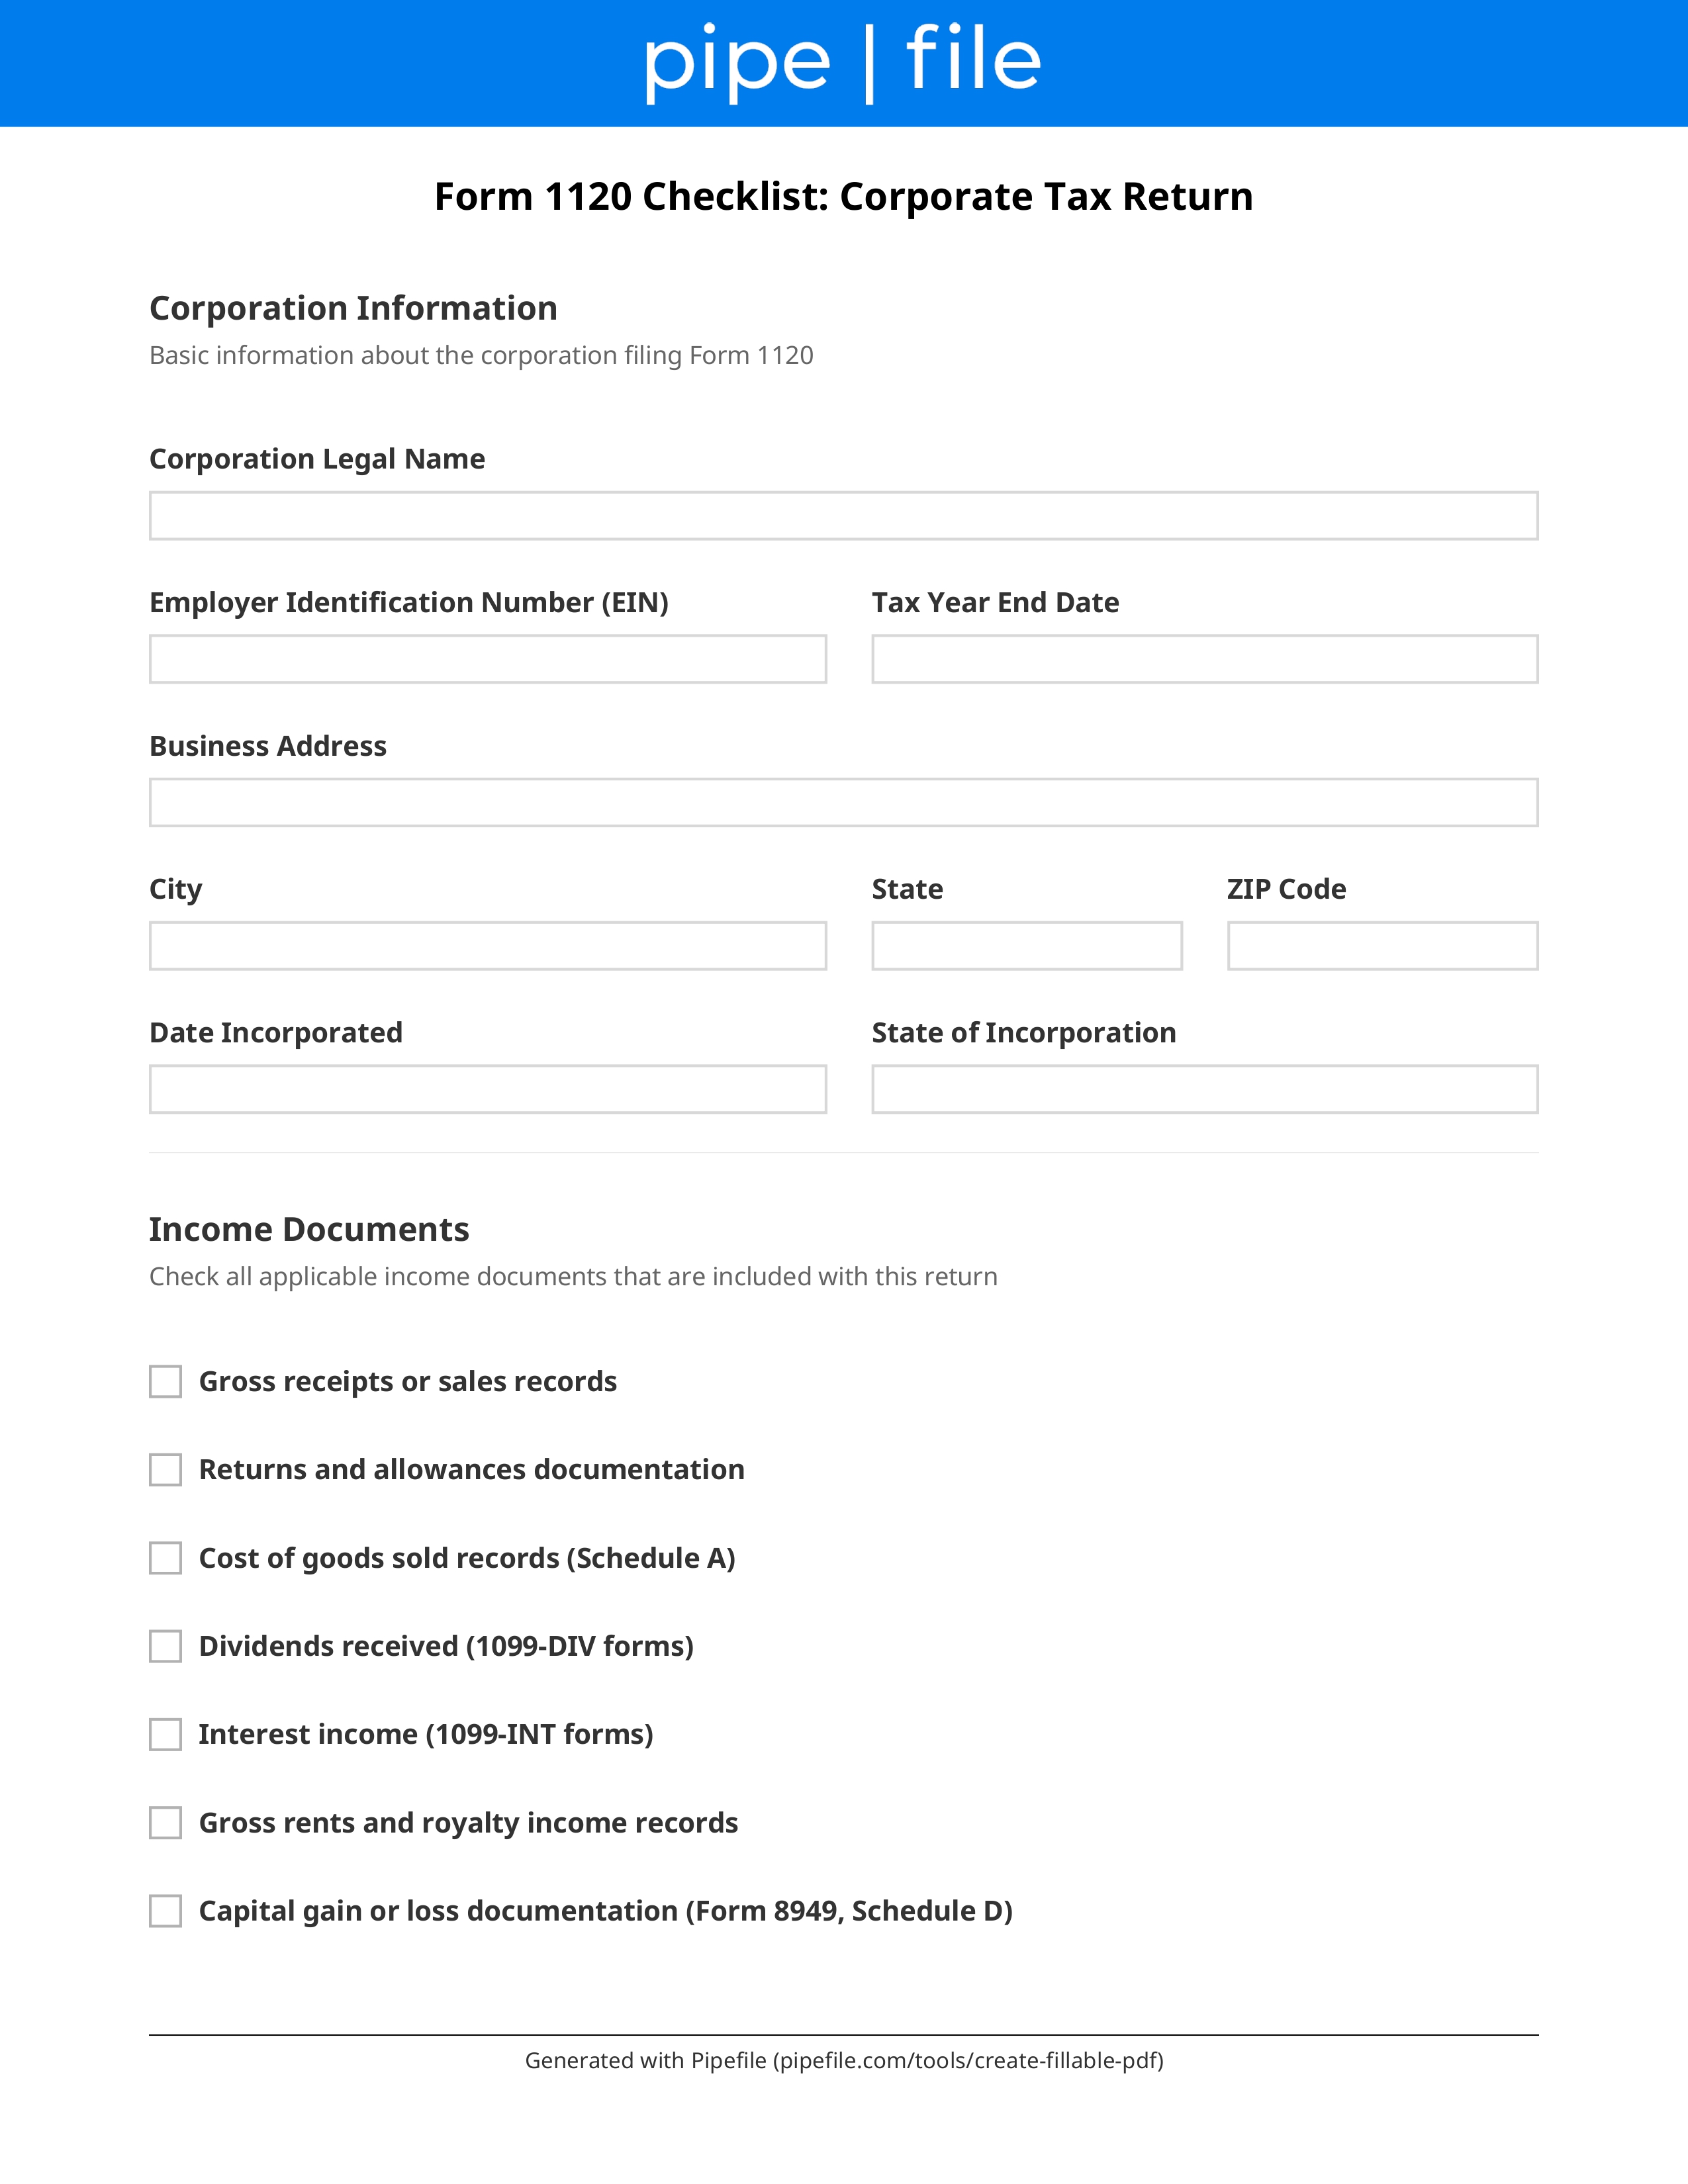
Form 1120 Checklist: Corporate Tax Return form template preview

Key Benefits

Reconcile book income to taxable income
Support depreciation and officer compensation
Track estimated tax and extension payments
Organize Schedule L, M-1, and M-2 data
Reduce PBC follow-ups during corporate filings
Professional C-corporation tax workflow

Common Use Cases

C corporations filing Form 1120CPAs preparing corporate income tax returnsControllers assembling corporate tax bindersMulti-entity groups consolidating 1120 dataFirms onboarding new corporate tax clientsYear-end close tied to corporate tax provision

Frequently Asked Questions

Who files Form 1120?
Domestic C corporations file Form 1120 to report income, gains, losses, deductions, and credits and to figure corporate income tax. S corporations generally file Form 1120-S instead.
What is Schedule M-1?
Schedule M-1 (or M-3 for larger corporations) reconciles book income to taxable income. Common items include depreciation differences, meals limitations, and tax-exempt income.
What officer compensation records are needed?
W-2 wages, bonuses, and related payroll tax records for officers. Reasonable compensation and related-party amounts are frequent review areas.
When is Form 1120 due?
Generally the 15th day of the fourth month after year-end (April 15 for calendar-year corporations), with extension available via Form 7004. Confirm current due dates for your year-end.

Checklist

Tax History

Prior-year Form 1120 and extension / payment records
Required

Opening balances, NOL carryovers, and credit carryforwards.

Books

Year-end financial statements and trial balance
Required

Book income is the starting point for Schedule M-1/M-3.

Reconciling Items

Book-to-tax difference schedule (M-1 or M-3 support)
Required

Depreciation, meals, reserves, and other permanent/temporary differences.

Assets

Fixed asset additions, disposals, and Form 4562 support
Required

Include §179 and bonus depreciation elections.

Compensation

Officer compensation detail and W-2s
Required

Required for Form 1120 compensation disclosures.

Payments

Estimated tax payments (Form 1120-W / vouchers) and refunds applied
Required

Reconcile to IRS transcripts when available.

Entity

Shareholder list and ownership percentages
Required

Note related corporations and consolidated return status.

State

State corporate return data and apportionment workpapers

Many states start from federal taxable income.