←Home/Templates/Finance/Accounting/Form 1099 Checklist: Independent Contractor Reporting Requirements

Form 1099 Checklist: Independent Contractor Reporting Requirements

CPA and Accounts Payable Resource

Complete year-end Form 1099 reporting with our checklist. For AP teams, CPAs, bookkeepers, and business owners issuing 1099-NEC, 1099-MISC, and related information returns. Collect W-9s, reconcile reportable payments, apply thresholds, and e-file or paper-file on time—including recipient copies. Confirm current IRS due dates and forms. Not tax advice.
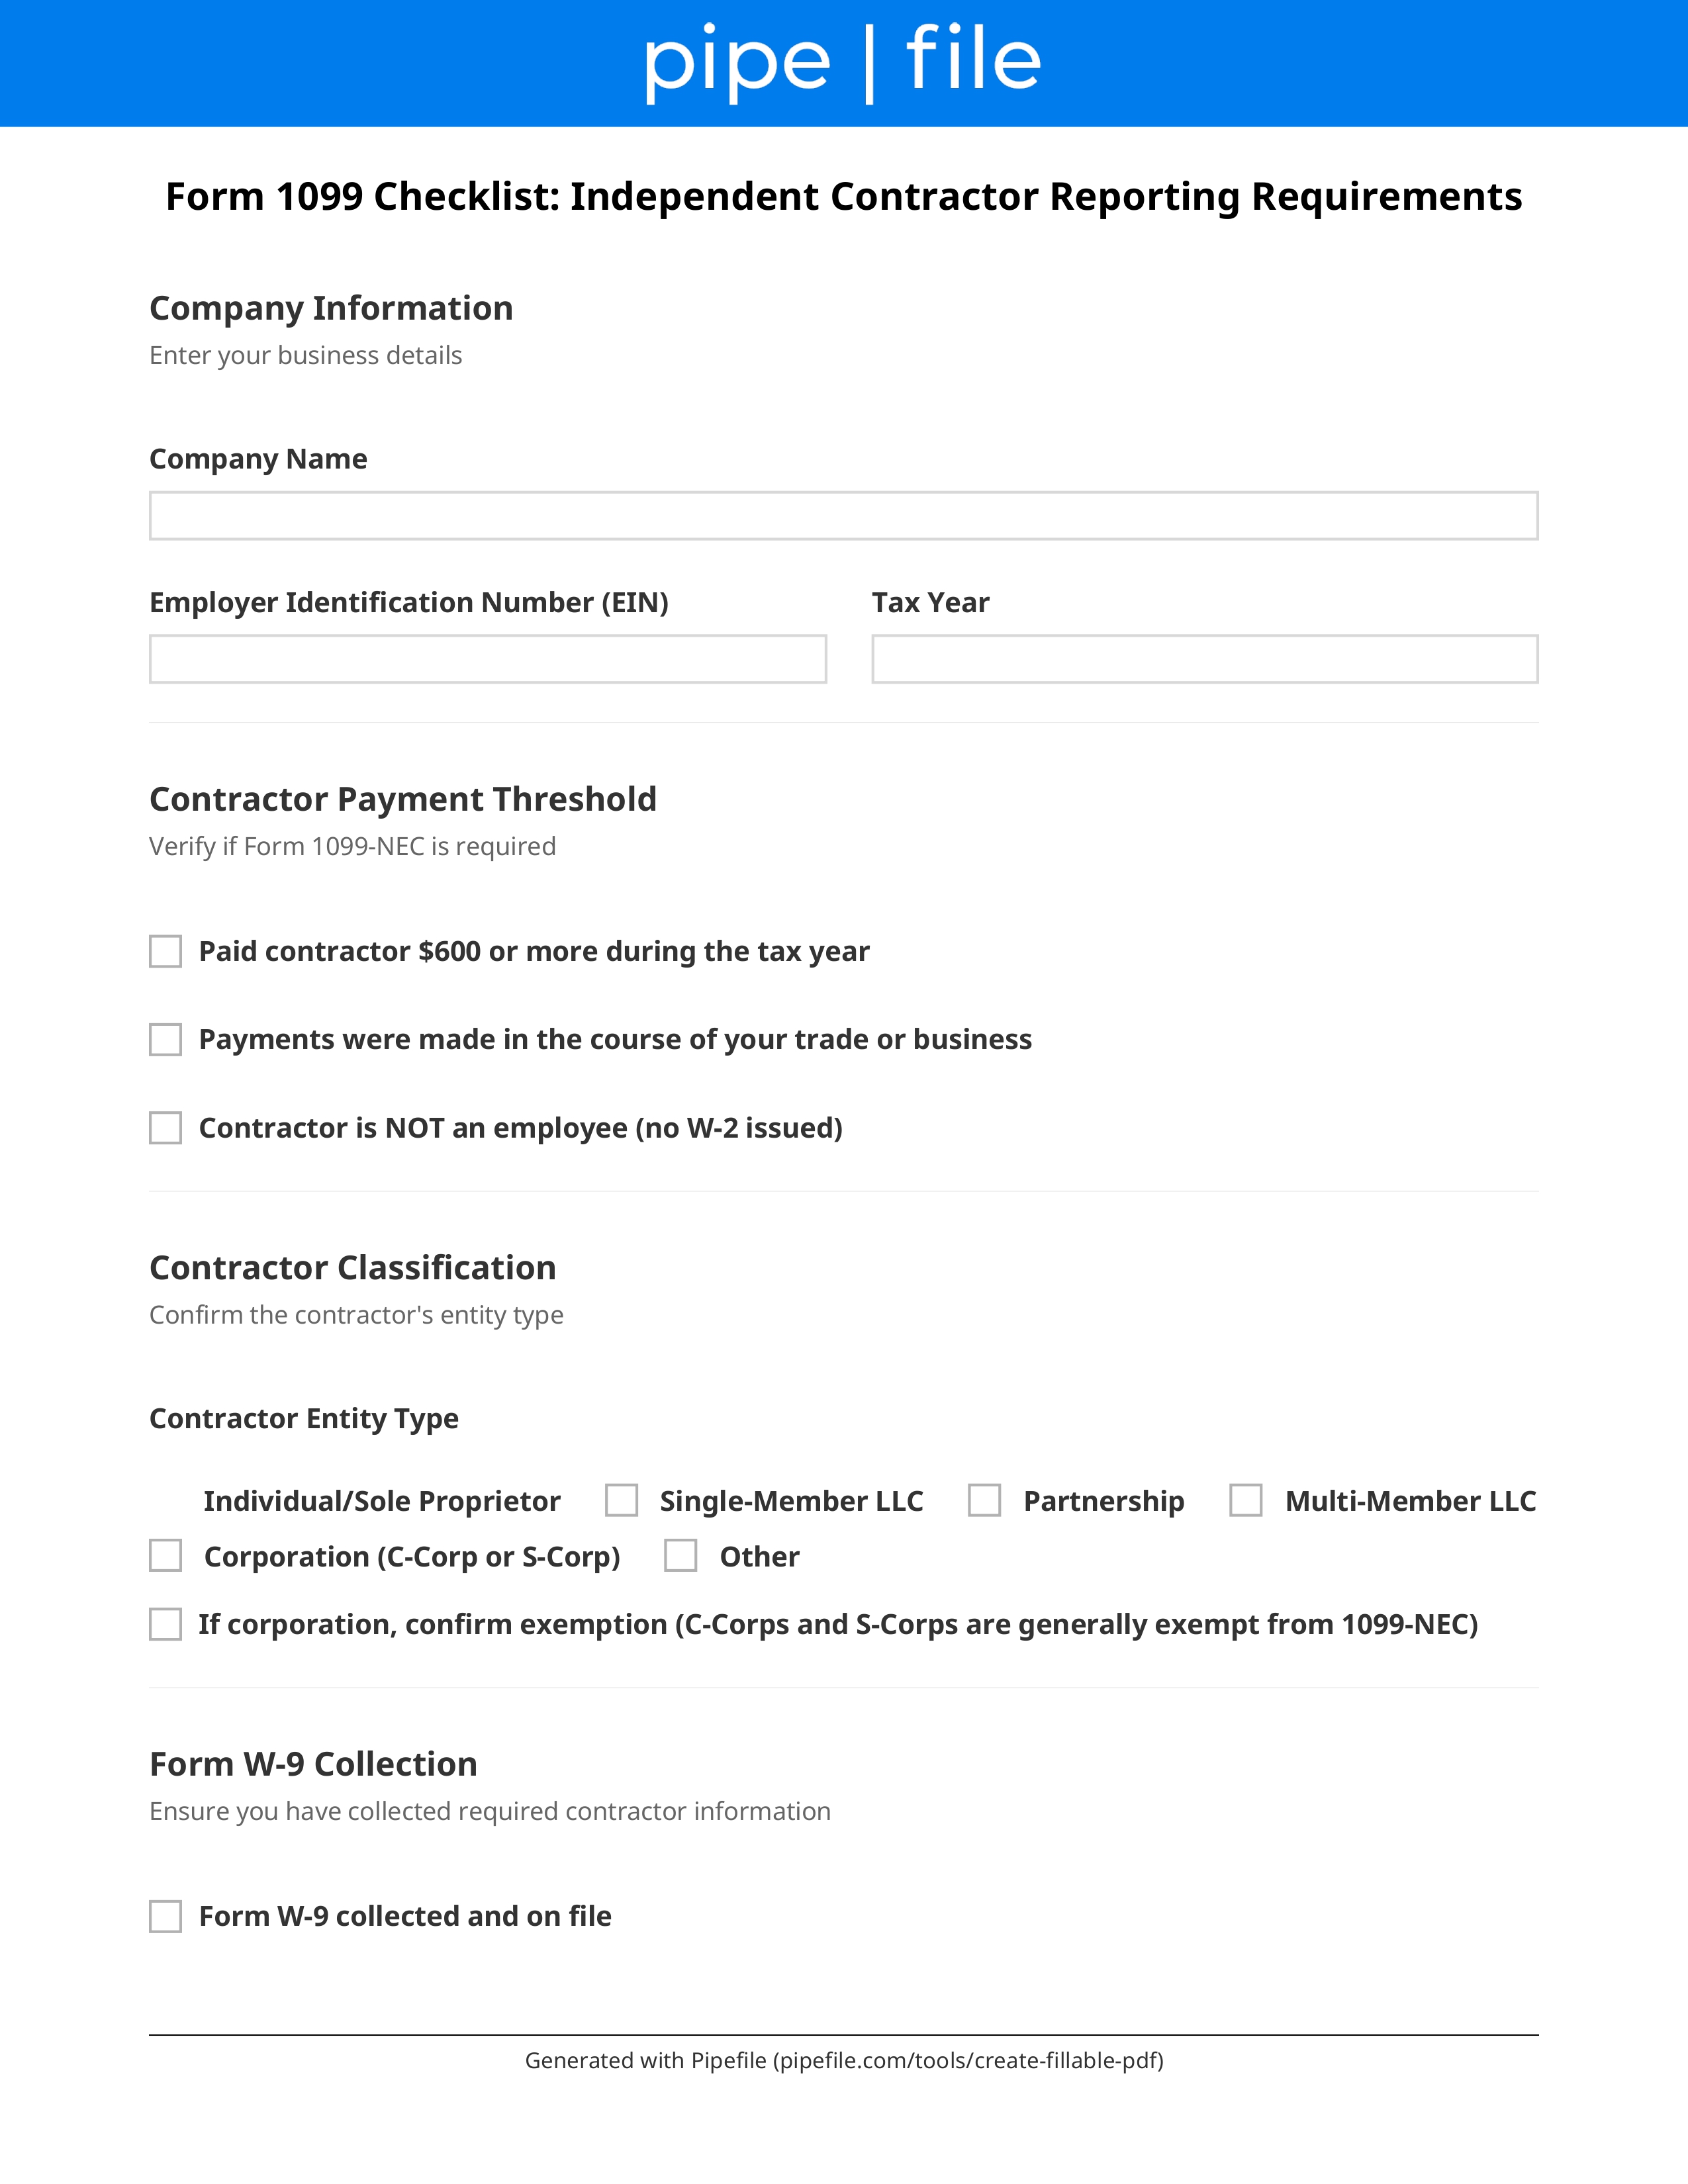
Form 1099 Checklist: Independent Contractor Reporting Requirements form template preview

Key Benefits

Collect W-9s before filing season
Identify payees over reporting thresholds
Separate 1099-NEC vs 1099-MISC payments
Reconcile AP totals to Forms 1099
Meet recipient and IRS e-file deadlines
Reduce penalties for late or incorrect returns

Common Use Cases

Year-end 1099-NEC filing for contractorsAP teams preparing vendor 1099sCPAs filing information returns for clientsBookkeepers reconciling contractor paymentsBusinesses correcting prior-year 1099sFirms managing backup withholding cases

Frequently Asked Questions

What is the difference between 1099-NEC and 1099-MISC?
Nonemployee compensation to independent contractors is generally reported on Form 1099-NEC. Form 1099-MISC covers other categories such as rents, prizes, and certain other income. Use the current IRS instructions for boxes and thresholds.
When are Forms 1099 due?
Recipient copies and IRS e-file/paper due dates vary by form and year. 1099-NEC deadlines are often earlier than some other 1099s. Confirm the current IRS due date chart before filing.
Do I need a W-9 for every payee?
Collect Form W-9 (or W-8 for foreign persons) before payment whenever you may need to file an information return. Without a TIN you may have backup withholding obligations.
What if I filed an incorrect 1099?
File a corrected Form 1099 as soon as you discover the error. Keep the original and corrected copies with your records and notify the recipient when required.

Checklist

Payee Data

Complete W-9 (or W-8) on file for each reportable payee
Required

Legal name and TIN must match IRS records to avoid B Notices.

Payments

Annual payment totals by payee from AP / accounting system
Required

Exclude or flag non-reportable payments per current IRS rules.

Review each payee against 1099 reporting thresholds
Required

Typically $600 for many 1099-NEC payments—confirm current amounts.

Forms

Map each payee to the correct form (1099-NEC, 1099-MISC, etc.)
Required

Do not put nonemployee compensation on the wrong form.

QC

Reconcile 1099 draft totals to the general ledger
Required

Investigate variances before e-file.

Filing

Furnish recipient copies by the IRS due date
Required

Mail or electronic delivery per consent rules.

E-file with IRS (or paper-file if eligible) and retain acceptance
Required

Electronic filing is required above certain volume thresholds.

Follow-Up

Process corrections and B Notice responses if issued
Required

Track TIN mismatches and re-solicit W-9s as required.