←Home/Templates/Finance/Lending/Business Line of Credit Checklist: Document Requirements

Business Line of Credit Checklist: Document Requirements

Working Capital and Commercial Lending Resource

Streamline your business line of credit application with our comprehensive document checklist. For owners, CFOs, and commercial lenders. A BLOC is revolving working-capital credit, so underwriters focus on cash flow, bank activity, existing debt, ownership, and personal guarantees. Gather financials, tax returns, statements, and entity documents so the bank can set a limit and close faster.
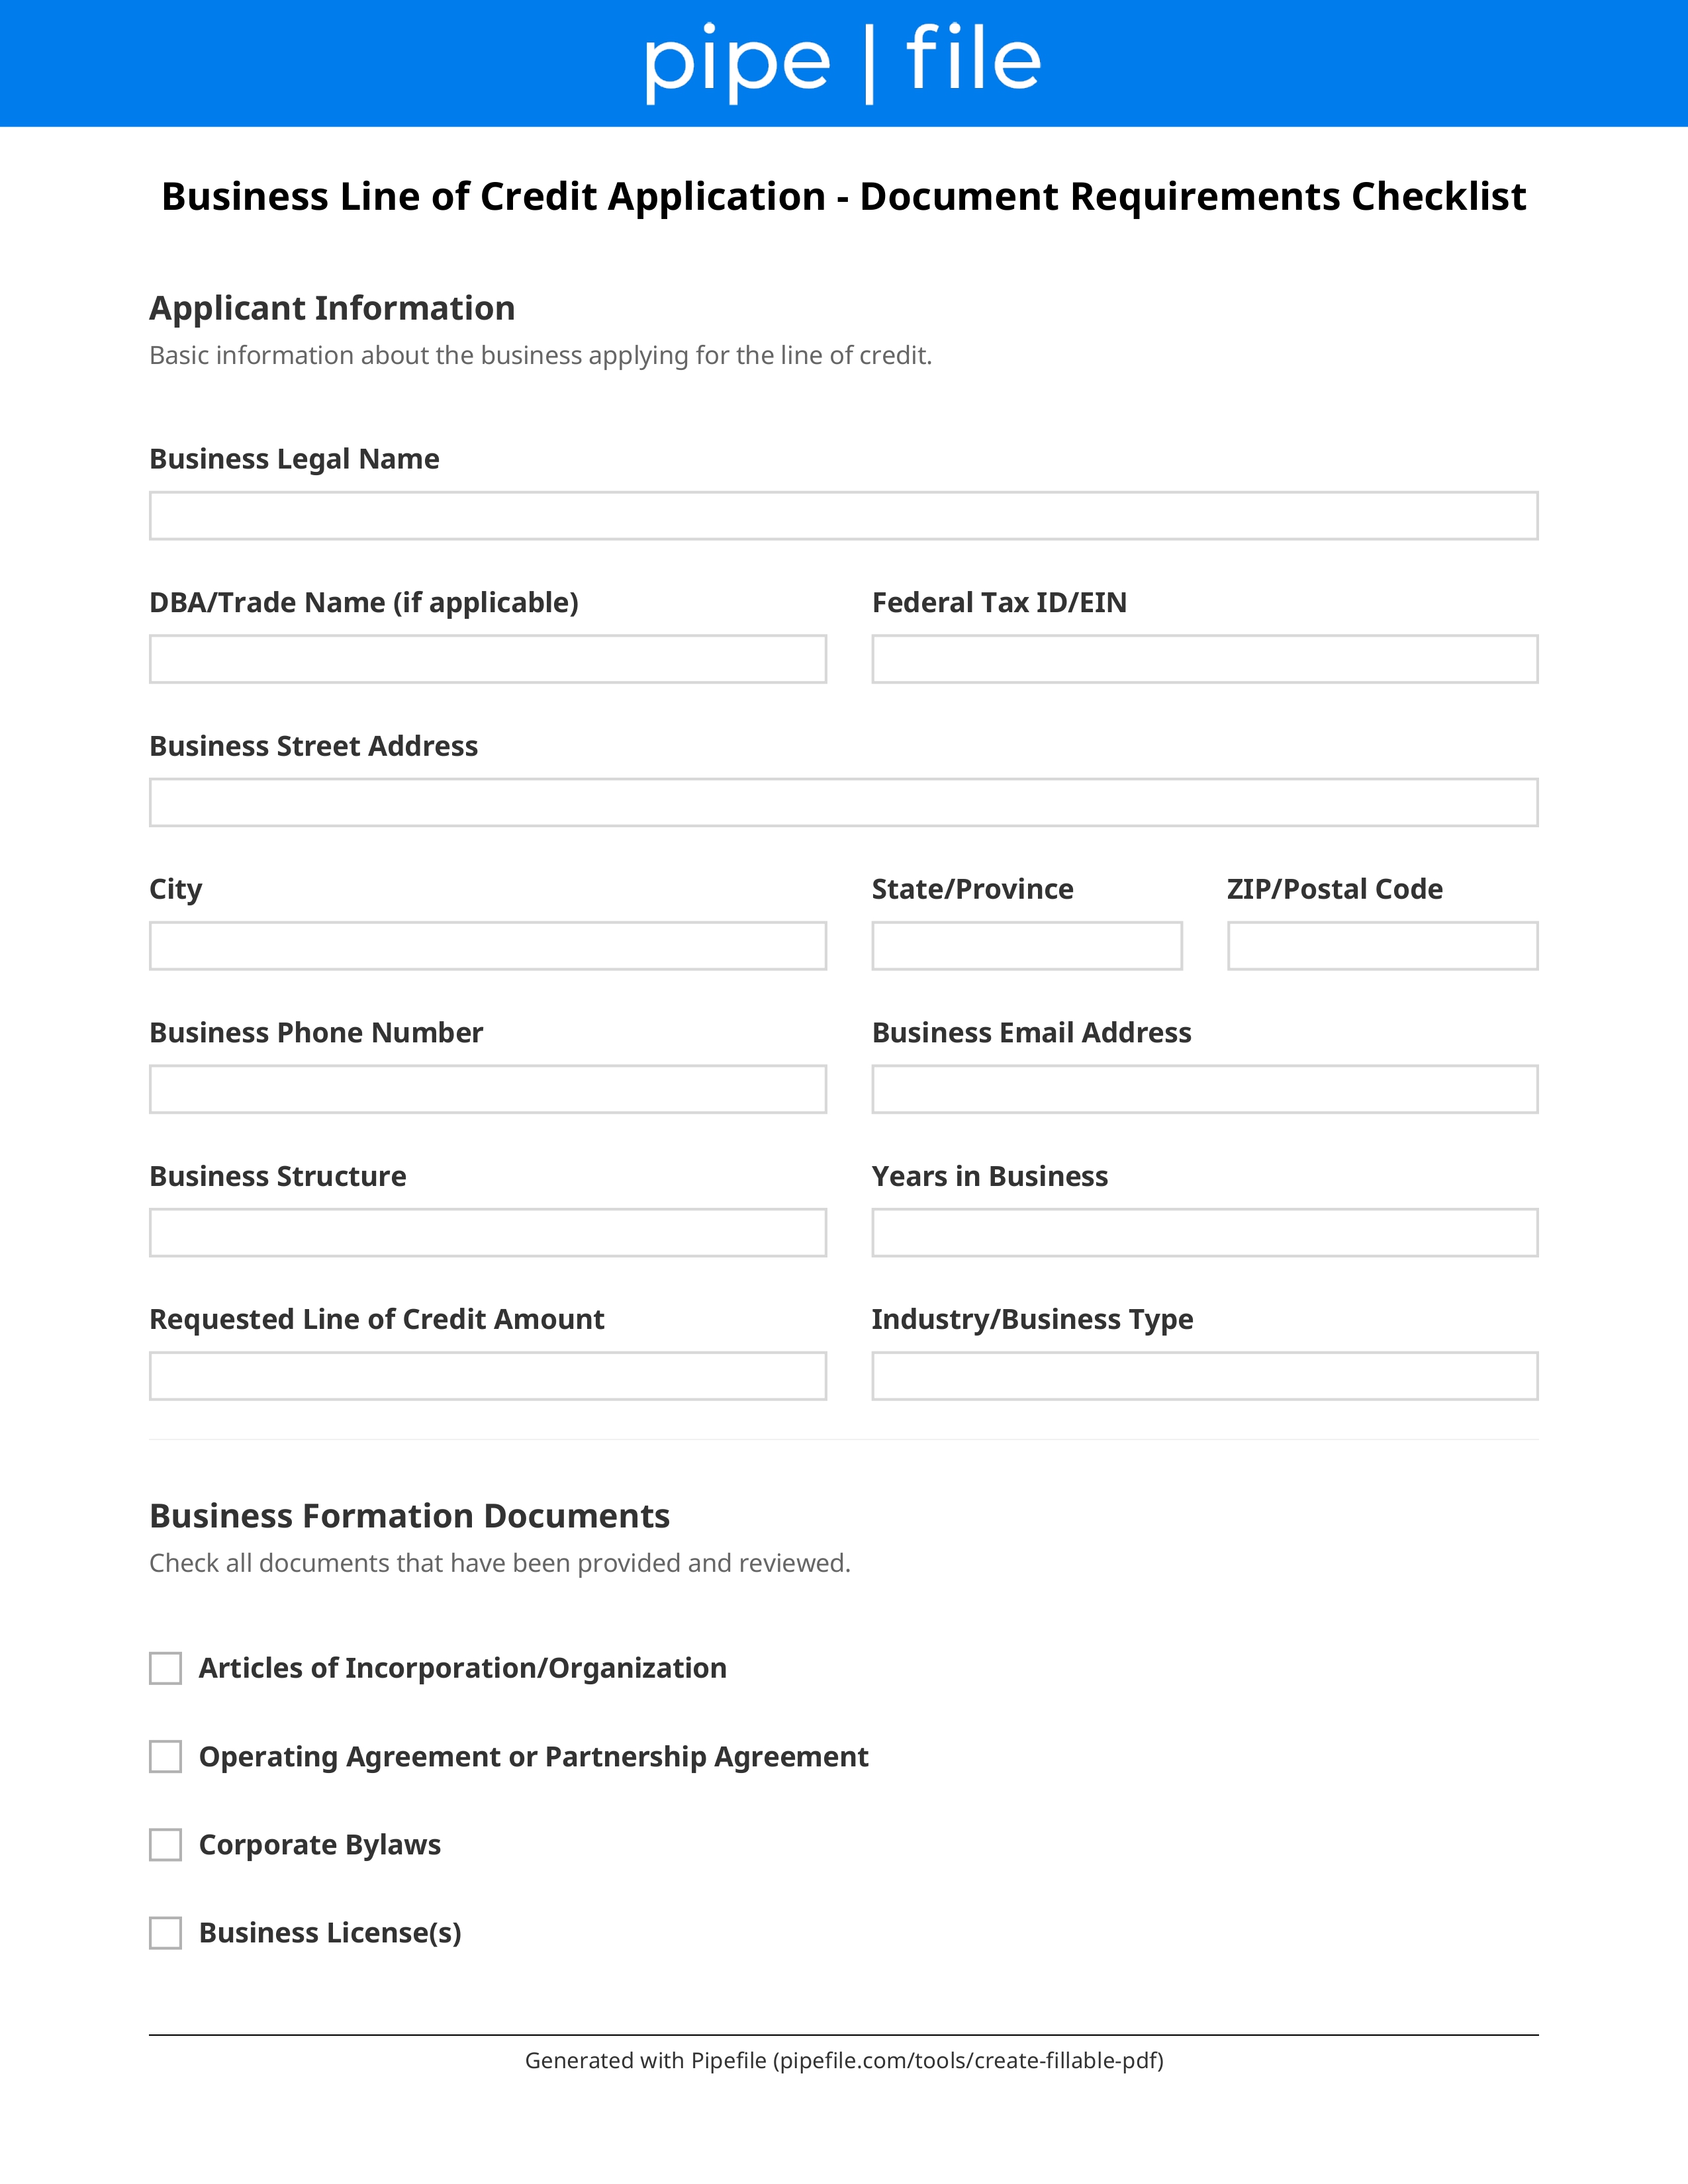
Business Line of Credit Checklist: Document Requirements form template preview

Key Benefits

Gather business and personal financials in one package
Document cash flow and bank activity for the credit limit
Prepare personal guarantees and ownership documents
List existing debt and contingent liabilities
Reduce conditions on revolving working-capital facilities
Professional commercial lending workflow

Common Use Cases

Owners applying for a new business line of creditCompanies renewing or increasing an existing BLOCCommercial lenders and credit analysts underwriting revolversCFOs assembling an annual bank packageStartups graduating from cards to a committed lineAdvisors preparing clients for working-capital financing

Frequently Asked Questions

What is a business line of credit?
A business line of credit is a revolving facility you can draw, repay, and redraw up to a limit. Interest is typically charged only on the outstanding balance. Banks use it for working capital, seasonality, and short-term gaps. It is not the same as a term loan or merchant cash advance.
What documents do banks want for a BLOC?
Expect 2-3 years of business tax returns and financials, YTD P&L and balance sheet, several months of business bank statements, a debt schedule, entity documents, ownership percentages, and personal financial statements plus tax returns for guarantors.
Will I need a personal guarantee?
Most small-business lines require a personal guarantee from owners above a set threshold (often 20%). The bank will pull personal credit and collect a personal financial statement. Some larger facilities are non-recourse; that is the exception.
How is the credit limit set?
Lenders look at cash flow, average deposits, existing debt service, collateral (receivables, inventory, or blanket UCC), and personal strength. A clean package with a debt schedule and recent statements helps them size the line without extra conditions.

Checklist

Application

Business line of credit application
Required

Legal name, EIN, ownership, requested limit, and use of the line.

Business and personal credit authorizations
Required

Required to pull commercial and consumer credit.

Financial Documentation

Business financial statements (2-3 years plus YTD P&L and balance sheet)
Required

Reviewed or compiled if available. Must tie to tax returns where applicable.

Business federal tax returns (2-3 years, all schedules)
Required

1120, 1120-S, 1065, or Schedule C as applicable.

Business bank statements (typically 3-12 months, all pages)
Required

Deposit accounts that support cash flow and average balances.

Schedule of business debt and contingent liabilities
Required

Loans, leases, cards, and guarantees. Shows capacity for a new revolver.

Business Documentation

Entity documents and ownership schedule (articles, operating agreement, EIN)
Required

Proves who owns and can bind the company.

Guarantor Documentation

Personal financial statement and personal tax returns for each guarantor
Required

Usually owners at 20% or more. Dated within the lender's window.