←Home/Templates/Insurance/Property Insurance Claim Checklist: Document Requirements

Property Insurance Claim Checklist: Document Requirements

Policyholder, Broker, and Adjuster Resource

Build a property-insurance claim file with a document checklist for policyholders, public adjusters, and brokers. Collect declarations and forms, photos of damage and pre-loss condition, inventories, contractor estimates, receipts for temporary repairs, and any sworn proof of loss the carrier requires. Claim duties and deadlines are in the policy and can be strict. Not insurance advice; confirm current reporting, mitigation, and proof-of-loss rules with the assigned adjuster. Pair with the home-insurance documents page for dwelling-specific lists.
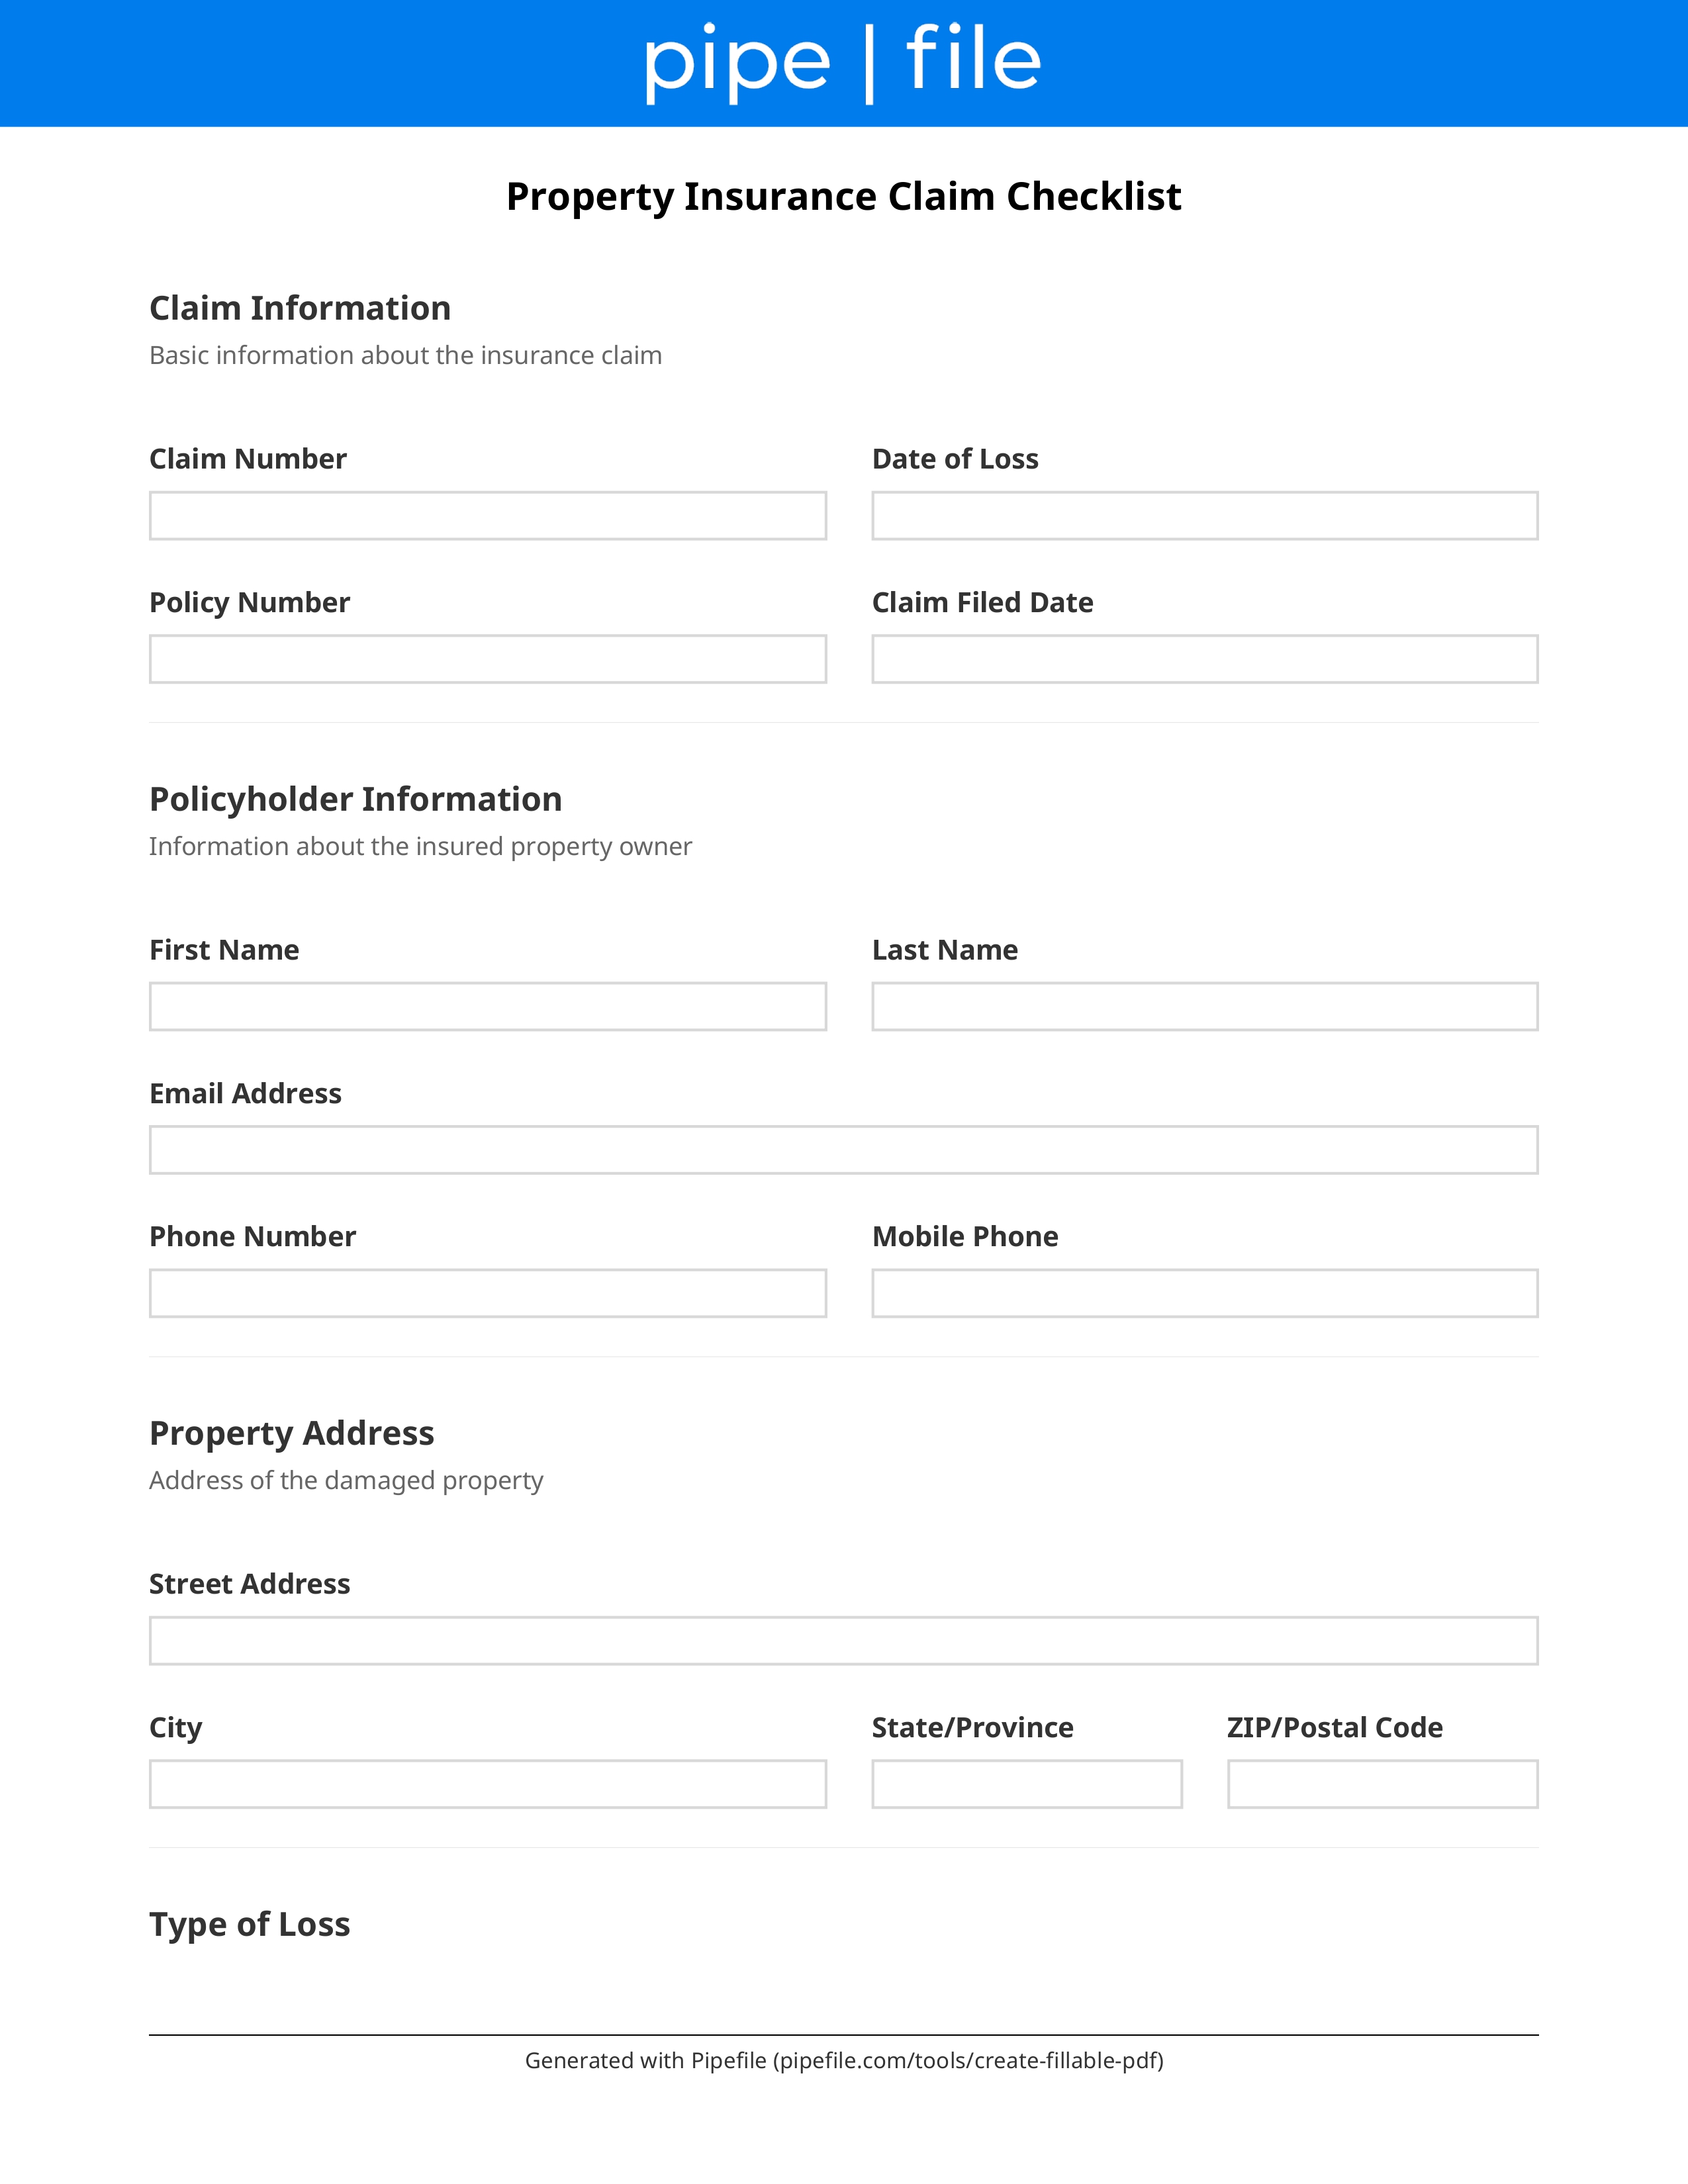
Property Insurance Claim Checklist: Document Requirements form template preview

Key Benefits

File the policy, endorsements, and claim number together
Organize dated photos of damage and pre-loss condition
Build a contents inventory with values and receipts
Collect contractor estimates and temporary-repair invoices
Track proof-of-loss due dates from the carrier letter
Keep mitigation steps documented

Common Use Cases

Fire, wind, hail, or water losses to a buildingCommercial location losses with business personal propertyResidential claims that need a structured document listPublic adjusters assembling a policyholder packageBrokers answering an adjuster’s request listClaims that later support a business-interruption worksheet

Frequently Asked Questions

What photos should we take?
Wide shots of each affected room or elevation, close-ups of damage, and any pre-loss photos you already have (listings, inventories). Date-stamp or keep the original phone metadata. Do not discard damaged items until the adjuster agrees, unless safety requires it.
What is a proof of loss?
A sworn statement of the amount claimed, often on the carrier’s form, due by a date in the policy or a demand letter. Missing it can jeopardize the claim. Ask the adjuster which form and deadline apply.
Should we make temporary repairs?
Most policies require you to protect the property from further damage. Keep invoices. Do not start permanent reconstruction before the adjuster has seen the loss unless the carrier directs you to.
Is this insurance advice?
No. Deductibles, exclusions (flood, earth movement), and claim duties are form-specific. Confirm current procedures with the carrier. This checklist does not determine coverage.

Checklist

Policy

Declarations, property forms, and deductibles for the location
Required

Include scheduled-equipment endorsements.

Notice

Claim number and written first-notice confirmation
Required

Date reported and to whom.

Evidence

Dated photos and video of damage and, if available, pre-loss condition
Required

Keep originals; do not only send compressed emails.

Inventory

Contents or BPP inventory with quantities, ages, and values

Receipts or bank records when you have them.

Estimates

Contractor estimates and any Xactimate or carrier estimate received
Required

Scope should match the damaged areas.

Mitigation

Temporary-repair and mitigation invoices (board-up, water extract)
Required

Required under many policies to prevent further loss.

Authorities

Fire, police, or weather reports related to the loss

Cause-of-loss support.

Proof of Loss

Sworn proof of loss and supporting worksheets if demanded

Calendar the due date on the carrier letter.